
Fees & Rates
Payment Processing Costs: A Complete Guide for Small Business Owners
Navigating the world of merchant services can feel like learning a second language. This guide breaks down exactly what you pay, why you pay it, and how to keep those fees as low as possible.
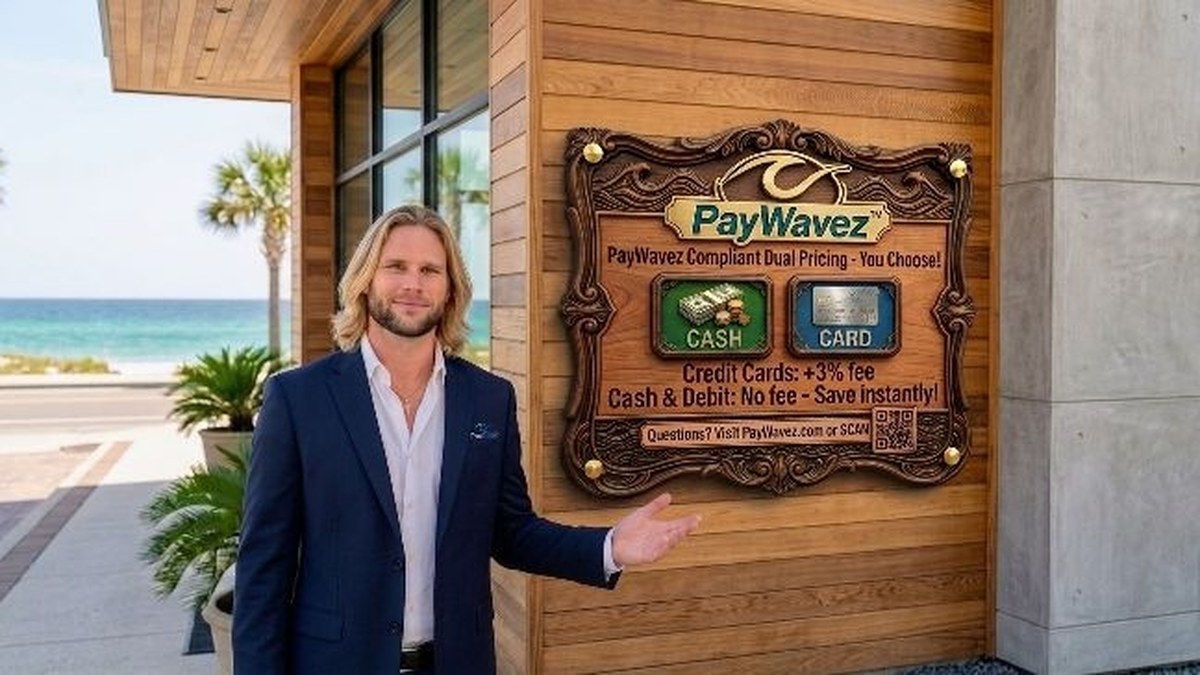
Understanding your payment processing costs is the first step toward keeping more of your hard-earned revenue. Every time a customer taps, dips, or swipes a card, a small portion of that sale disappears into a complex web of banks and technology providers. For most small business owners, these fees feel like a moving target that is impossible to hit. If you have ever wondered why your monthly statement looks different every time, you are not alone. To get a baseline of the numbers, you should first check out our detailed breakdown on how much are card processing fees to see the current industry averages.
The Three Main Pillars of Processing Fees
When you look at your merchant statement, it helps to think of your costs in three distinct buckets. The first is interchange. This is the fee set by the card brands like Visa and Mastercard, and it goes directly to the bank that issued the customer's card. This fee is non-negotiable for everyone, from the smallest coffee shop to the biggest big-box retailer. It changes based on the type of card used—debit cards are cheap, while high-end rewards cards are expensive.
The second bucket is assessments. These are small fees paid directly to the card brands themselves for using their network. Like interchange, these are set in stone and your processor has no control over them. The third bucket is the processor markup. This is where your merchant services provider makes their money. This is also the only part of the fee structure that is truly negotiable. It covers the cost of the technology, the customer support, and the risk the processor takes on your behalf.
The average small business pays between 2.5% and 3.5% in total credit card processing fees, but businesses using dual-pricing models often reduce their out-of-pocket costs to nearly zero.
Payment processing costs for different pricing models
Not all merchant accounts are billed the same way. The "how" of your billing often matters more than the "how much." There are three main ways processors charge small businesses: Flat Rate, Interchange Plus, and Tiered Pricing. Flat rate pricing is popular because it is simple. You pay one percentage (like 2.9% + $0.30) regardless of the card type. While easy to understand, it is often the most expensive option for high-volume businesses because the processor keeps the extra margin when a low-cost debit card is used.
Interchange Plus is widely considered the most transparent model. The processor passes the exact cost of interchange and assessments through to you, then adds a small, fixed markup (like 0.20% + $0.10). This allows you to see exactly what you are paying for. Tiered pricing is the one to watch out for. It groups transactions into "qualified," "mid-qualified," and "non-qualified" buckets. It often looks cheap on the surface, but most of your sales will likely get pushed into the expensive non-qualified tiers, driving up your total bill.
Transparency in your merchant statement is the only way to truly control your overhead and ensure your business remains profitable.
Hidden Fees That Inflate Your Bill
Beyond the percentage per transaction, many small businesses get nickeled and dimed by "junk fees." These can add hundreds of dollars to your monthly costs without providing any real value. Common culprits include statement fees, which charge you just to receive a bill, and PCI non-compliance fees. If you haven't filled out your annual security questionnaire, your processor might be charging you $30 to $100 a month in penalties. Other fees to watch for include batch header fees, which are charged every time you close out your terminal for the day.
At PayWavez, we believe in transparency. We encourage business owners to see a live demo of our platform to see how we handle reporting and fee structures. If you are operating in the Southeast, you might even want to look at our regional support in Alabama payment processing or specific local help like Pensacola credit card processing. Knowing your local representative can often help you spot these hidden fees before they drain your bank account.
The Impact of Surcharging and Cash Discounts
One of the most effective ways to manage payment processing costs is to stop paying them entirely. Surcharging and cash discount programs (often called dual pricing) have become incredibly popular for US small businesses. A surcharge program adds a small fee (usually around 3% to 4%) to every credit card transaction. This fee covers the processing cost, meaning the business owner receives 100% of the sticker price of the item.
Cash discounting works slightly differently by offering a lower price to customers who pay with cash or debit. Both methods are legal in most states, provided you follow specific signage and disclosure rules. This shifts the cost of the convenience of using a credit card from the business owner to the customer who chooses to use that card. For many service-based businesses or retailers with tight margins, this can be the difference between a profitable month and a loss.
Hardware and POS System Expenses
Your processing fees aren't just about the software; the hardware matters too. A basic countertop terminal might cost a few hundred dollars, while a full Point of Sale (POS) system with inventory management and employee tracking can cost thousands. Some processors offer "free" equipment, but be careful—this usually comes with a much higher transaction rate or a long-term contract that is hard to break. It is often cheaper in the long run to buy your equipment upfront or use a lease-to-own model that doesn't lock you into predatory rates.
Modern terminals also support contactless payments (NFC), which can actually help reduce costs by lowering the risk of fraud. When a customer uses a chip or a mobile wallet like Apple Pay, the transaction is more secure than a traditional swipe. More security means fewer chargebacks, and chargebacks are one of the most expensive "hidden" costs in the industry. Every time a customer disputes a charge, you could be hit with a fee ranging from $15 to $50, even if you win the dispute.
How to Calculate Your True Effective Rate
Don't let a processor tell you your rate is 1.9%. The only number that matters is your effective rate. To find this, take the total fees you paid for the month and divide them by your total sales volume. For example, if you processed $10,000 in sales and paid $300 in total fees, your effective rate is 3%. This number includes everything—interchange, markups, and junk fees. If your effective rate is consistently above 3.5% and you aren't in a high-risk industry, you are likely overpaying and should look for a new provider.
In conclusion, managing your payment processing costs requires constant vigilance. By understanding the difference between interchange and markup, avoiding tiered pricing, and considering dual-pricing models, you can protect your bottom line. Always remember to check back with our core guide on how much are card processing fees to ensure your current provider is staying competitive with the rest of the market.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.