Compliance & Legal
Is Dual Pricing on Debit Cards Compliant? The Merchant’s Guide to Legal Card Processing
As credit card fees continue to eat into small business margins, many owners are looking for ways to pass those costs along without breaking the law or upsetting customers.
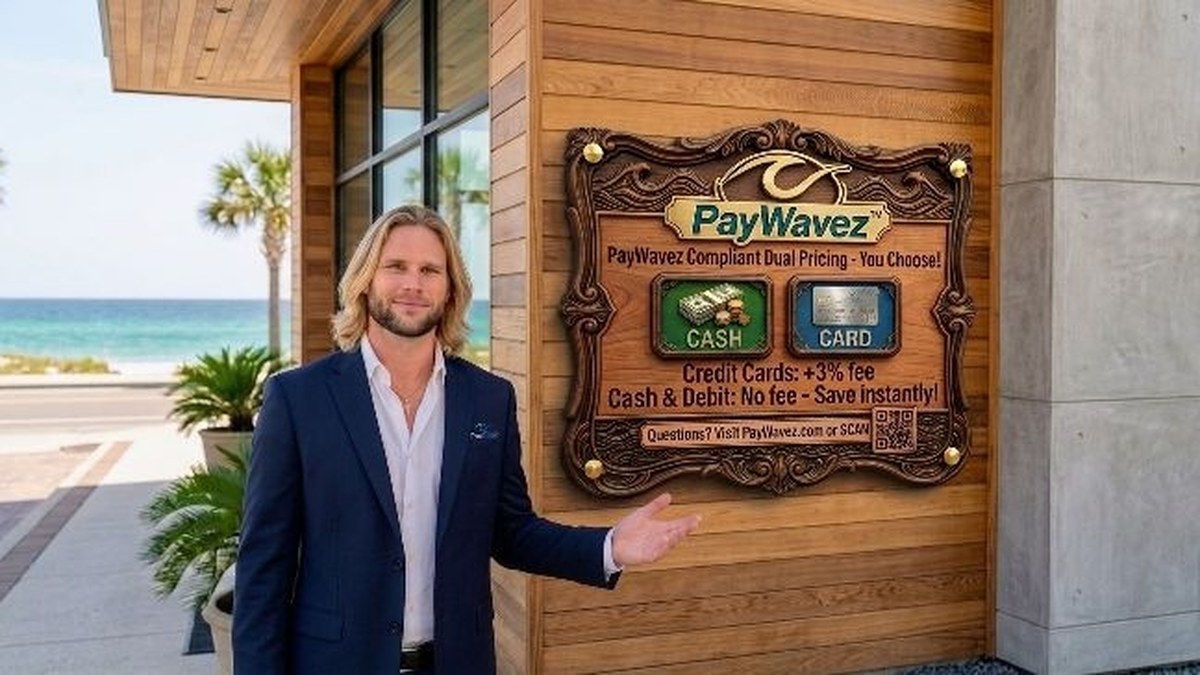
Many business owners are asking, is dual pricing on debit cards compliant, as they look for ways to offset rising processing costs. The short answer is yes, but the "how" matters more than the "what." In the world of merchant services, there is a massive difference between adding a fee at the checkout and offering two different prices for a product. If you get this distinction wrong, you could face heavy fines from card brands like Visa and Mastercard. If you get it right, you can virtually eliminate your processing bill while staying fully within the law.
The Core Difference: Dual Pricing vs. Surcharging
To understand if your setup is legal, you first have to understand what you are actually doing. Many people use the terms "surcharge," "cash discount," and "dual pricing" as if they mean the same thing. They do not. A surcharge is a fee added to a credit card transaction at the point of sale. Under federal law and card brand rules, you cannot surcharge a debit card, even if it is run as "credit."
Dual pricing is different. With dual pricing, you are simply displaying two prices for every item: a cash price and a card price. Because you aren't adding a "fee" to the transaction, but rather presenting the customer with a choice between two established prices, it circumvents the strict rules that govern surcharging. This is why dual pricing is the preferred method for modern businesses in Destin and across the Gulf Coast.
Why Is Dual Pricing on Debit Cards Compliant While Surcharging Isn't?
The legality of dual pricing boils down to the Durbin Amendment and card brand operating regulations. Surcharging is strictly limited to credit cards. If a customer pulls out a debit card—even one with a Visa logo—and you add a 3% fee to the total, you have committed a compliance violation. This is a common trap for businesses using older equipment or poorly configured software.
However, dual pricing is considered compliant on debit cards because it is a transparent pricing model. You are not "penalizing" the debit user; you are offering a standard price for card payments and a lower price for cash. As long as both prices are clearly displayed on your shelf tags and your POS system handles the math correctly, you are following the rules. You can see how this looks in action by viewing our live demo.
According to industry audits, over 85% of merchants who attempt to manage their own surcharge programs accidentally charge a fee on a debit card at least once a month, risking immediate account termination.
The Role of the Durbin Amendment
The Durbin Amendment is a piece of federal legislation that changed how debit card fees work. It capped the amount that large banks could charge for debit transactions. Because debit cards are tied directly to a bank account, they are treated more like digital checks than lines of credit. This is why the government and the card brands protect debit card users so fiercely. When you ask, "is dual pricing on debit cards compliant," you are really asking if your program respects the protections laid out in the Durbin Amendment. A true dual-pricing program does exactly that by avoiding the "fee" label entirely.
Signage and Disclosure Requirements
Compliance isn't just about what happens inside the credit card terminal; it is about what the customer sees before they even reach for their wallet. To stay compliant, you must have clear signage at the entrance of your business and at the point of sale. This signage must inform the customer that there is a difference between the cash price and the card price.
- Signs must be at least 8.5 x 11 inches at the entrance.
- Signage must be visible at every register.
- The POS system must print both the cash price and the card price on the receipt.
If you are a business owner looking for Alabama payment processing, you know that local customers appreciate transparency. Hiding fees is the fastest way to lose a regular. Dual pricing keeps everything out in the open, which is why it has become the gold standard for compliance-focused merchants.
Compliance isn't just about following rules; it's about protecting your brand's reputation with transparent pricing that customers can trust.
Common Mistakes That Lead to Fines
The biggest mistake merchants make is trying to "do it themselves" by manually adding a fee or using a calculator under the counter. If your receipt shows a line item labeled "Service Fee" or "Non-Cash Adjustment" on a debit card transaction, you are at risk. Card brands have "secret shoppers" who visit businesses specifically to check for these violations. If they catch you surcharging a debit card, the fines can range from $5,000 to $25,000 for a first offense.
Another mistake is failing to update your shelf tags. If your tags only show the cash price, but the register charges the card price, you are technically engaging in deceptive pricing. A compliant dual-pricing program ensures that the customer knows exactly what they will pay regardless of their payment method.
How PayWavez Simplifies Compliance
We built PayWavez to take the guesswork out of these regulations. Our systems are pre-configured to handle dual pricing automatically. When you scan an item, the terminal shows the customer both prices. If they swipe a debit card, the system knows how to process that transaction without triggering a surcharge violation. We handle the signage, the software updates, and the back-end reporting so you can focus on running your business.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.