
Fees & Compliance
Is Dual Pricing Illegal? The Merchant's Guide to Legal Card Processing
Many business owners worry about the legality of passing card fees to customers. We break down the state laws, network rules, and signage requirements you need to know.
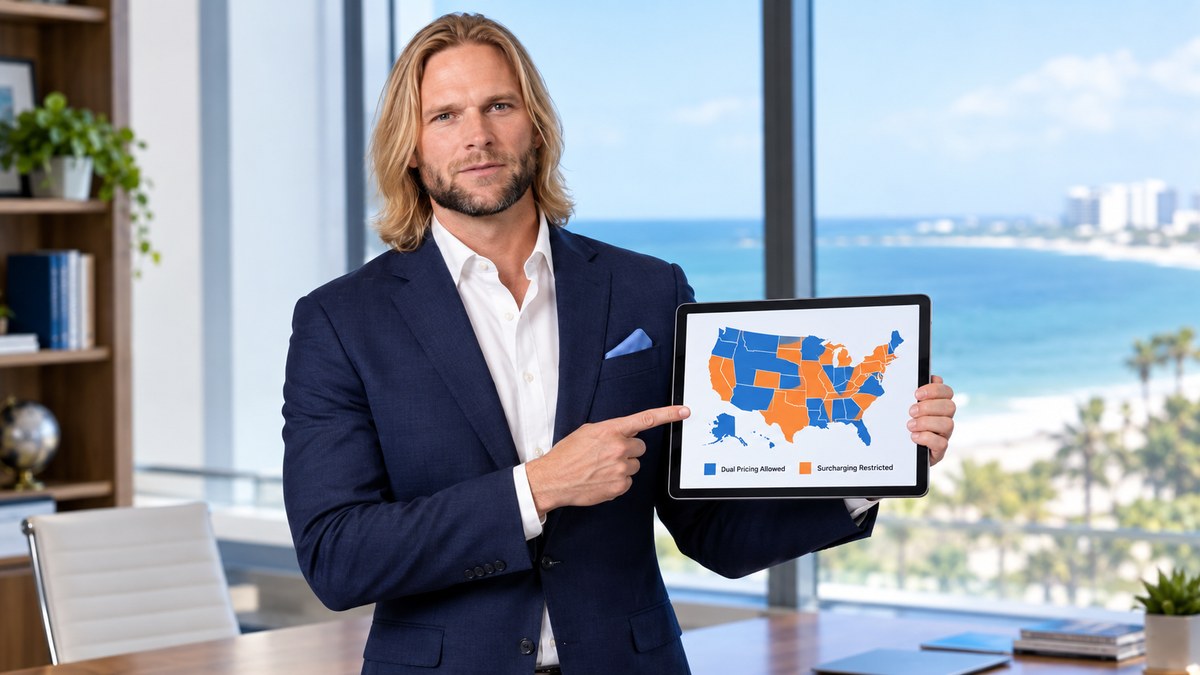
When merchants first hear about programs that eliminate their processing costs, the first question they ask is, "is dual pricing illegal?" It is a fair question, especially since the rules around credit card fees have changed many times over the last decade. For years, credit card companies like Visa and Mastercard had strict rules that prevented small businesses from charging different prices based on the payment method. However, legal settlements and new state laws have opened the door for merchants to take control of their overhead costs.
The Short Answer: Is Dual Pricing Illegal?
In the vast majority of cases, the answer is no. Dual pricing is a legal and transparent way for a business to offer two different prices for every item or service: one price for cash and one price for credit cards. Unlike surcharging, which adds a fee at the end of a transaction, dual pricing clearly displays both prices upfront. This transparency is why dual pricing is widely considered the most compliant way to handle card processing costs in the United States.
While the practice is legal on a federal level, there are specific rules you must follow to stay in the clear. These rules come from three different places: federal law, state law, and the card brands (Visa, Mastercard, Discover, and Amex). If you ignore these rules, you could face fines or even have your merchant account shut down. That is why it is so important to work with a processor that understands the nuances of Alabama payment processing and national compliance standards.
The Legal Landscape: Is Dual Pricing Illegal in Your State?
As of 2026, dual pricing is legal in all 50 states. However, it is often confused with "surcharging," which is still restricted in a few places like Connecticut and Massachusetts. Even in those states, dual pricing is generally viewed differently because it is a multi-price model rather than an added fee model. When you show a customer that an item is $10.00 for cash and $10.40 for credit, you are giving them a choice between two established prices. This is legally distinct from telling them an item is $10.00 and then adding a 4% fee at the register.
Small businesses that switch to a dual pricing model typically see a 95% to 100% reduction in their monthly credit card processing fees, saving thousands of dollars per year.
For businesses in the Florida Panhandle looking for Destin credit card processing, the rules are very favorable. Florida has historically protected the right of merchants to offer discounts for cash, and dual pricing fits perfectly within those protections. The key is making sure your point-of-sale system is programmed correctly to handle these two price points without manual math by your employees.
Dual Pricing vs. Surcharging: Why the Difference Matters
Many people use the terms "dual pricing," "surcharging," and "cash discounting" interchangeably, but they are not the same thing. Understanding the difference is vital for staying legal. Surcharging is the act of adding a fee (usually capped at 3% or 4%) to a credit card transaction. Surcharging has many restrictions: it cannot be applied to debit cards (even if run as credit), it requires 30-day notice to card brands, and it requires specific register signage.
Dual pricing is much simpler. Because you are presenting two separate prices, you are not "adding a fee." You are simply offering two different rates for the same product. This model is often preferred by card brands because it provides the most clarity to the consumer. You can see how this looks in practice by viewing our live demo. When the customer sees both options clearly, they don't feel like they are being hit with a hidden cost at the last second.
Transparency is the best defense against compliance issues. When a customer sees both prices clearly, there is no confusion or feeling of being overcharged.
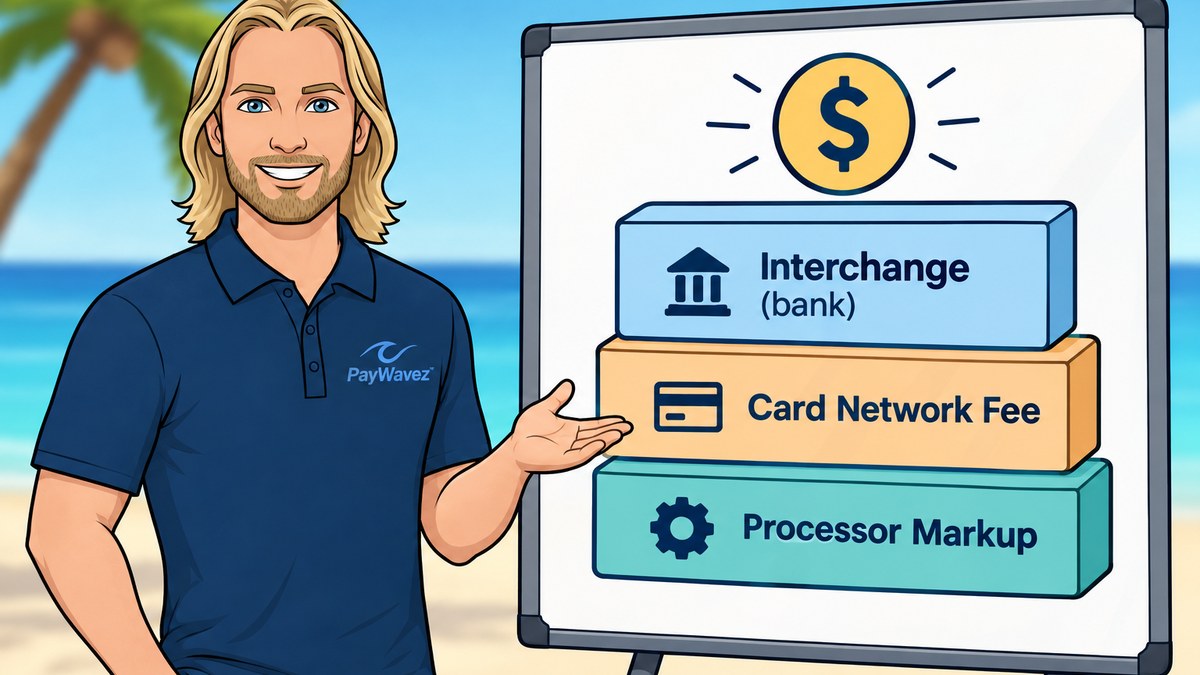
Signage and Transparency Requirements
Even though dual pricing is legal, you cannot just start doing it without telling your customers. Transparency is the number one requirement. To stay compliant, you must have clear signage at your entrance and at the point of sale. These signs should inform customers that there is a difference in price based on the payment method used. Most processors will provide these signs for you to ensure the wording meets legal standards.
Furthermore, your receipts must clearly show which price was applied. If a customer pays with a card, the receipt should reflect the card price. If they pay with cash, it should show the cash price. Modern POS terminals handle this automatically, ensuring that your records are clean in the event of an audit or a chargeback dispute. Failing to provide this level of detail is one of the quickest ways to turn a legal program into a compliance nightmare.
Visa and Mastercard Rules for 2026
The card brands have updated their merchant rules several times in recent years to address dual pricing. Their main focus is on the "consumer experience." They want to ensure that cardholders are not being misled. One of the most important rules to remember is that you cannot charge more for a credit card transaction than what it actually costs you to process that transaction. For most businesses, this means capping the price difference at around 3% to 4%.
Another critical rule involves debit cards. Under the Durbin Amendment, you are generally not allowed to add a surcharge to a debit card transaction. However, dual pricing is often viewed as a way to circumvent this because it is a price-per-item model rather than a fee-per-transaction model. Still, it is best practice to work with a processor that can automatically detect the card type and apply the correct pricing logic to keep you 100% compliant with federal regulations.
How to Avoid Fines and Legal Trouble
The easiest way to get into trouble is to try and "DIY" your dual pricing program. Some merchants try to just tell customers about a fee verbally or write it on a chalkboard. This is a recipe for disaster. If a secret shopper from a card brand visits your store and sees that you aren't following signage rules, they can fine your merchant bank, and those fines will be passed down to you.
To stay safe, follow these steps:
- Use a terminal or POS system that is specifically programmed for dual pricing.
- Display the required signage at the door and the register.
- Ensure your receipts clearly break down the pricing.
- Train your staff to explain the program as a "choice" for the customer.
- Regularly review your merchant statements to ensure your effective rate is where it should be.
Ready to Stop Paying Processing Fees?
Now that you know the answer to "is dual pricing illegal?" is a resounding no, it is time to look at how much you could be saving. Most small businesses are losing thousands of dollars every month to processing fees that could be better spent on marketing, inventory, or hiring. Dual pricing isn't just about saving money; it's about creating a sustainable business model where your costs don't grow every time you make a sale.
At PayWavez, we specialize in helping merchants navigate these rules so they can keep more of their hard-earned money. Whether you are a retail shop in Alabama or a restaurant on the Gulf Coast, we have the tools and the expertise to get you set up legally and quickly. Don't let processing fees eat your profits any longer.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.