
Fees & Rates
Credit Card Processing Fees Explained: A Simple Guide for Business Owners
Understanding your merchant statement shouldn't require a finance degree. We break down exactly what you are paying for every time a customer swipes their card.
Credit card processing fees explained: if you own a small business, you know that every time a customer pays with plastic, a small piece of that sale disappears. These costs are a necessary part of doing business in a world that rarely uses cash, but they can be incredibly frustrating. Many business owners look at their monthly merchant statement and see a long list of codes, percentages, and flat fees that make very little sense. It feels like the goal of the industry is to keep you in the dark so you don't notice when rates go up. Before we dive into the details, you should check out our guide on how much are card processing fees to get a baseline for what you should be paying.
What are Credit Card Processing Fees?
At its simplest, these fees are the price you pay for the ability to accept electronic payments. When a customer taps their phone or slides their chip card, a complex network of banks and technology providers works together to move money from the customer's account to yours. Each of these players takes a small cut for their trouble. For a business owner, these fees are usually deducted from your daily deposits or billed as a lump sum at the end of the month. If you are operating in the Gulf Coast region, perhaps running a retail shop in Destin, you need to know exactly where every penny is going to keep your margins healthy.
Most small businesses pay an average effective rate between 2.5% and 4.0% once all fees, markups, and monthly costs are factored into the total volume.
The Three Main Components of Your Rate
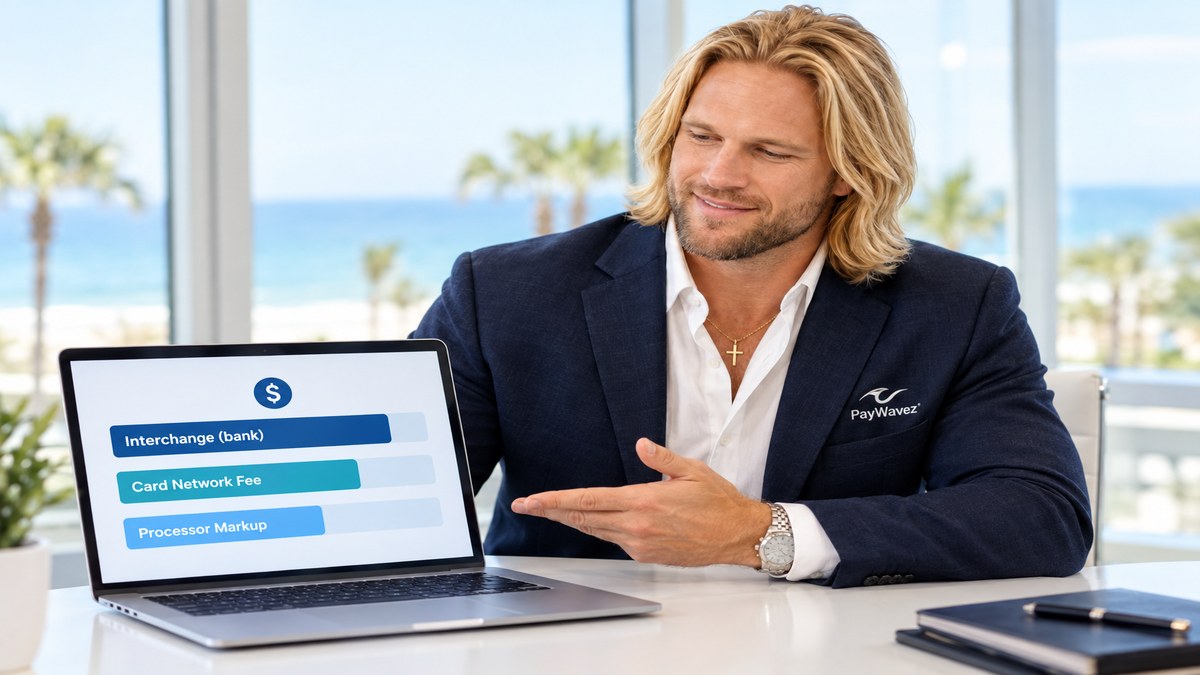
Every credit card transaction fee is made up of three distinct parts. You can think of it like a three-layer cake. The first layer is interchange. This is the fee set by the card brands like Visa and Mastercard, but it is paid to the bank that issued the card to the customer. This is non-negotiable; every processor pays the same interchange rates. The second layer is the assessment fee. This goes directly to the card brands (Visa, Mastercard, Discover) for the use of their network. Like interchange, this is the same for everyone. The third layer is the processor markup. This is the only part of the fee that you can actually negotiate. This is how your merchant services provider makes money and covers their overhead for customer support and equipment.
Understanding these layers is vital because it helps you see where your money is going. If a salesperson tells you they can lower your interchange rates, they are lying. Nobody can change interchange. However, a good partner can lower their own markup or help you choose a pricing model that fits your specific business volume. If you want to see how this looks in action, you can view our live demo of our payment solutions.
Credit card processing fees explained: Pricing Models
How you are billed is often more important than the actual percentage you pay. There are three common ways processors charge small businesses. The first is Flat-Rate pricing. This is what companies like Square or PayPal use. You pay one set percentage (like 2.6% + $0.10) for every transaction, regardless of the card type. This is easy to understand but usually more expensive for high-volume businesses because the processor keeps the difference when a low-cost card is used.
The second model is Tiered pricing. This is the most confusing and often the most expensive. The processor groups transactions into "qualified," "mid-qualified," and "non-qualified" buckets. They lure you in with a low qualified rate, but almost no cards actually qualify for it. Most sales end up in the expensive non-qualified bucket. We generally recommend avoiding this model entirely. The third model is Interchange-Plus. This is the most transparent. You pay the exact cost of the interchange fee plus a fixed markup from the processor. This allows you to see exactly what you are paying the bank versus what you are paying your processor.
The most expensive fee is the one you don't understand on your merchant statement. Transparency is the only way to protect your profits.
Merchant Accounts and Terminals
To accept cards, you need a merchant account. This is a special type of bank account that holds your credit card funds before they are deposited into your regular business checking account. Getting approved for a merchant account involves a quick credit check and a review of your business type. Once approved, you need equipment. This could be a simple mobile card reader that plugs into your phone, or a full-featured Point of Sale (POS) system. Modern terminals handle more than just payments; they can manage inventory, track employee hours, and even run loyalty programs. Whether you are looking for Alabama payment processing or service across the country, your hardware choice will impact your daily workflow and your security.
Surcharging and Cash Discount Rules
One of the most effective ways to handle high processing costs is to pass them on to the customer. This is called surcharging. In most states, you can legally add a small fee (usually up to 4%) to any transaction where a customer uses a credit card. However, there are strict rules you must follow. You must post clear signage at the entrance and at the register, and the surcharge must be listed as a separate line item on the receipt. You also cannot surcharge debit cards, even if they are run as "credit."
An alternative is the Cash Discount program. This is where you list your prices as "cash prices." If a customer pays with a card, they pay the standard price, but if they pay with cash, they receive a discount. This is often easier to manage legally and is generally better received by customers. Both methods allow you to keep more of your hard-earned money by offsetting the cost of the technology required to accept cards.
Chargebacks and Hidden Fees
Beyond the per-transaction rates, there are other costs to watch out for. Chargebacks occur when a customer disputes a charge with their bank. Even if you win the dispute, you are often charged a fee (ranging from $15 to $50) just for the processing of the claim. Other hidden fees might include PCI compliance fees, which are charged if you don't keep your security standards up to date, or "statement fees" which are basically just a charge for sending you a bill. A transparent processor will be upfront about these costs and help you avoid them whenever possible.
How to Lower Your Fees Today
The first step to lowering your costs is to perform a statement audit. Look at your total fees divided by your total sales volume. This gives you your "effective rate." If that number is significantly higher than 3%, you are likely overpaying. You can also look into Level 2 or Level 3 processing if you sell to other businesses (B2B), as this can significantly lower interchange rates. Finally, don't be afraid to switch providers if your current one keeps raising rates without warning. For a deeper dive into the math, revisit our post on how much are card processing fees to see where you stand. At PayWavez, we pride ourselves on transparency and helping small business owners keep their profits where they belong.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.