
Fees & Rates
How to Get a Credit Card Machine With No Fees for Your Business
Stop letting credit card processing fees eat your profit margins by switching to a zero-cost processing model that works for your small business.
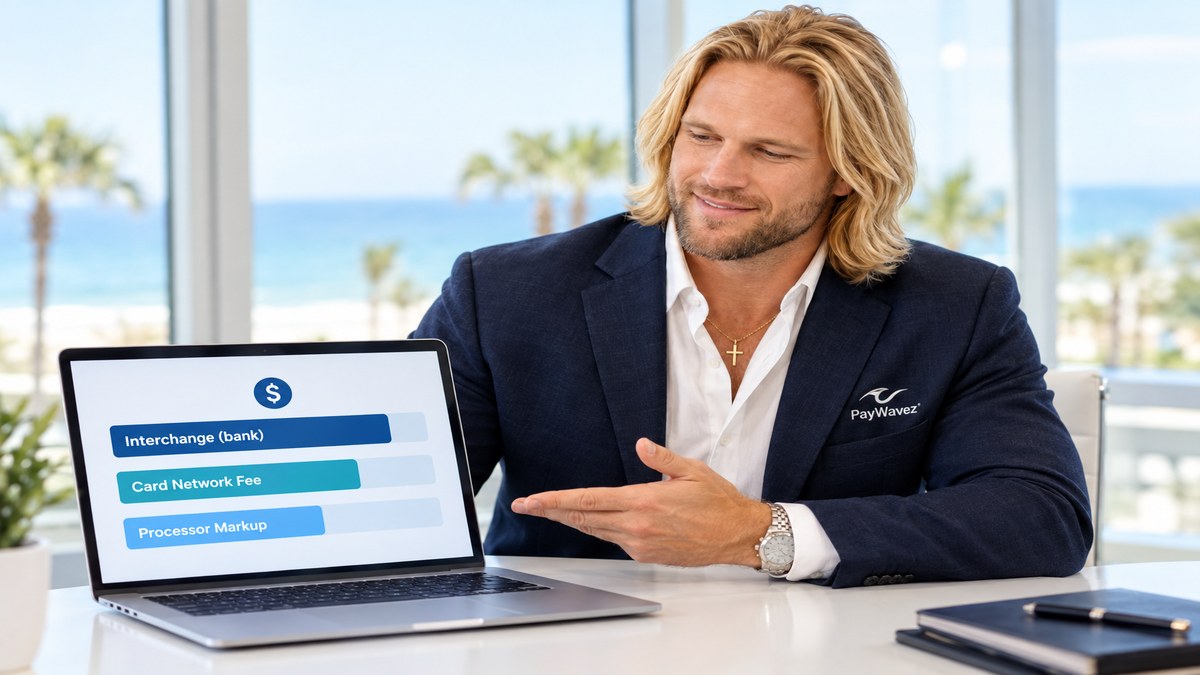
Credit card machine with no fees is a phrase that every small business owner wants to hear. For years, merchants have accepted that losing 3% or 4% of every sale is just the cost of doing business. But in 2026, that is no longer the case. New technology and updated card brand rules allow you to eliminate those processing costs entirely. By using programs like dual pricing or surcharging, you can ensure that the amount you see on the screen is the exact amount that hits your bank account.
What is a credit card machine with no fees?
When people search for a credit card machine with no fees, they are usually looking for two different things. First, they want a physical terminal that does not cost hundreds of dollars upfront. Second, and more importantly, they want a merchant account where the monthly processing fees are zero. A true zero-fee setup uses a program where the customer pays the processing cost instead of the business owner. This is often called 'zero-cost processing' or 'fee-free processing.'
In a traditional setup, if you sell a product for $100, the bank takes about $3.00, and you keep $97.00. With a no-fee machine, the customer pays $100 plus a small service fee, or you offer a lower price for cash. Either way, you keep the full $100. This shift can save a small business thousands of dollars every single month. You can see how this looks in action by viewing our live demo.
How Dual Pricing Eliminates Merchant Costs
Dual pricing is currently the most popular way to get a credit card machine with no fees. It is different from a surcharge. With dual pricing, your terminal displays two different prices for every item: a card price and a cash price. The card price is slightly higher to cover the cost of the transaction. This is perfectly legal in all 50 states and is very easy for customers to understand because they see it at gas stations every day.
The beauty of dual pricing is its transparency. When a customer walks up to your counter, the terminal shows them exactly what they will pay based on their choice of payment. Because the 'card price' already includes the processing fee, the merchant (you) ends up with the full 'cash price' in your bank account. This eliminates the headache of trying to calculate your effective rate at the end of the month.
Small businesses that switch to zero-cost processing models save an average of $850 to $1,200 per month for every $30,000 in card volume they process.
Surcharging vs. Cash Discounting: Which is Better?
While dual pricing is the gold standard, you might also hear about surcharging or cash discounting. Surcharging is when you add a specific percentage (usually up to 3%) to a credit card transaction at the point of sale. However, you cannot surcharge on debit cards. This makes it a bit more complicated for your staff to manage. Cash discounting is when you post a 'credit price' and offer a discount to anyone who pays with cash.
For most retailers and restaurants, dual pricing is the better choice because it is the most compliant and least confusing for the customer. If you are looking for Alabama payment processing, you will find that many local shops have already made this switch to protect their margins against inflation. Whether you choose a surcharge or dual pricing, the goal remains the same: stop paying the bank out of your own pocket.
Passing the fee to the customer is the only way to reach true zero-cost processing and stop the monthly drain on your business bank account.
Choosing the Right Terminal for Your Storefront
To run a no-fee program, you need a smart terminal that can handle the math for you. You cannot use an old-fashioned 'dumb' terminal that only takes one price input. You need a device that can automatically calculate the cash vs. card price or apply a surcharge in real-time. Modern terminals like the Clover Duo or the PAX A-series are perfect for this. They connect to the internet via Wi-Fi or cellular and update their software automatically to stay compliant with card brand rules.
If you operate a specialized business, like a shop on the coast, you need hardware that is as fast as your foot traffic. For example, business owners looking for Destin credit card processing often choose mobile smart terminals so they can take payments out on a patio or at a sidewalk sale without losing the ability to pass on those fees.
Are There Any Truly "Hidden" Costs?
When a provider promises a credit card machine with no fees, you should always check the fine print for 'ancillary' costs. While the processing fees (the 3%) might be gone, there are usually small fixed costs involved in running a merchant account. These can include PCI compliance fees, which ensure your business is secure, or monthly gateway fees for online payments.
A transparent processor will show you these fees upfront. Even with a $20 or $30 monthly service fee, a business doing $20,000 in sales is still saving nearly $600 a month compared to traditional processing. The 'no fee' promise refers to the variable percentage that usually makes up 95% of your bill. Always ask for a statement review to see exactly what you are currently paying and what you will save.
The Legal Side: State Laws and Compliance
It is important to know that while dual pricing is legal everywhere, surcharging has specific rules. For instance, you must post a sign at your entrance and at the register informing customers that a fee applies to credit card transactions. You also cannot charge more than what the processor charges you, with a hard cap of 3% or 4% depending on the current card brand regulations.
Failing to follow these rules can result in heavy fines from Visa or Mastercard. This is why working with a professional payment partner is vital. We handle the signage requirements and the terminal programming so you don't have to worry about the legal details. We stay on top of the changing laws so your business stays protected.
Why Most "Free" Offers Aren't Actually Free
You have likely seen ads for 'Free Credit Card Machines.' Usually, these companies give you a $200 terminal for free but then lock you into a three-year contract with very high rates. You end up paying for that 'free' machine ten times over in hidden fees. A better approach is to find a processor that offers fair hardware pricing and a zero-fee processing model.
The value isn't in the $200 piece of plastic; the value is in the $10,000 a year you save by not paying processing percentages. Don't get distracted by a free terminal if the rates are going to bankrupt you. Look at the total cost of ownership over a year, not just the cost of the device on day one.
How to Switch to a Zero-Fee Model
Switching to a credit card machine with no fees is easier than most owners think. First, you need a copy of your most recent merchant statement. This allows a pro to see your current volume and fee structure. Next, you choose your hardware and the type of program (Dual Pricing or Surcharge) that fits your business style. Once the new terminal arrives, you simply plug it in, set up your new signs, and start saving money on your very first transaction.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.