
Fees & Rates
Payment Processing Fee Guide: What You Really Pay and Why
Understanding every payment processing fee on your merchant statement is the first step toward reclaiming your profit margins.
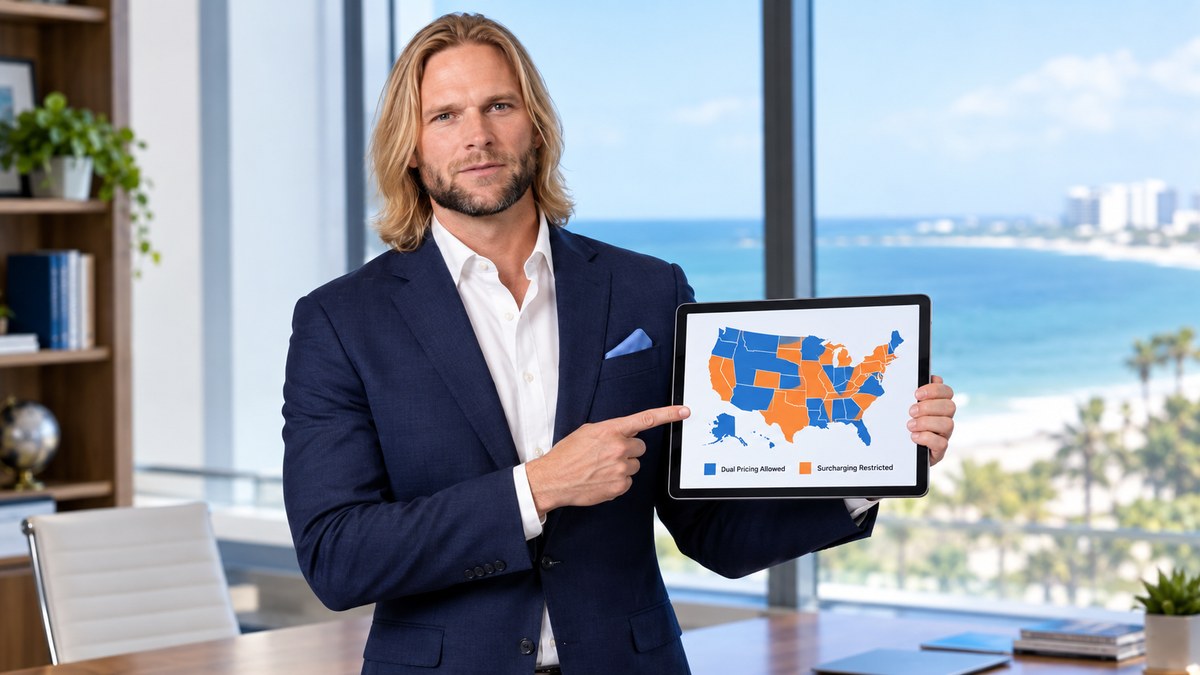
A payment processing fee is the cost a merchant pays to accept credit and debit card payments from customers. For many small business owners, these costs feel like a moving target that eats away at monthly profits without much explanation. Before we dive into the complex mechanics of these rates, it is helpful to understand the baseline of how much are card processing fees in the current market. Knowing the average helps you spot when your processor is taking more than their fair share.
The Three Parts of Every Payment Processing Fee
When you see a single percentage on your statement, it is actually a combination of three distinct costs. You cannot negotiate all of them, so it is vital to know which part is set in stone and which part is flexible. The first part is the interchange fee. This is the largest portion of the fee and goes directly to the bank that issued the customer's card (like Chase or Wells Fargo). The card brands, such as Visa and Mastercard, set these rates twice a year.
The second part is the assessment fee. This goes to the card brands themselves for the right to use their network. Like interchange, assessments are non-negotiable. The third part is the processor markup. This is the only part of the payment processing fee that you can actually negotiate. This is the profit your merchant services provider makes for handling the transaction, providing the equipment, and offering customer support.
Understanding Every Payment Processing Fee on Your Statement
Merchant statements are notoriously difficult to read. They often hide costs behind industry jargon or bundle them into confusing categories. To truly understand your costs, you must look beyond the headline rate. You might see fees for PCI compliance, which is the security standard for handling card data. Some processors charge a monthly minimum fee if you do not process enough volume. Others might hide "statement fees" or "gateway fees" for online transactions.
One of the most expensive ways to pay is through tiered pricing. In this model, the processor labels transactions as "qualified," "mid-qualified," or "non-qualified." While the qualified rate looks low, almost no modern cards (like rewards or business cards) actually qualify for it. This results in a much higher payment processing fee than you were originally promised during the sales pitch. We always recommend looking at your "effective rate," which is your total fees divided by your total sales volume.
Flat-Rate vs. Interchange-Plus Pricing
Many new businesses start with flat-rate processors like Square or PayPal. These companies charge a single percentage for every transaction, regardless of the card type. While this is simple, it is often the most expensive way to grow. As your volume increases, you are overpaying for basic debit cards that should cost much less to process. Interchange-plus pricing is more transparent. It shows you the exact cost of the interchange and then adds a small, fixed markup. This model ensures that when a low-cost card is swiped, you get the savings instead of the processor keeping the difference.
The most expensive fee is the one you didn't know you were paying. Transparency in merchant services isn't just about honesty; it is about your bottom line.
How Terminals and POS Systems Affect Your Costs
The hardware you use in your business has a direct impact on your payment processing fee. When you dip a chip card or use tap-to-pay on a modern terminal, the transaction is considered "card-present." These transactions have the lowest rates because the risk of fraud is very low. If you manually type a card number into a computer or a virtual terminal, the fee jumps significantly. This is because "card-not-present" transactions are higher risk for the banks.
Choosing the right Point of Sale (POS) system is about more than just ringing up sales. A good system helps you track these costs in real-time. If you are a service business in Gulf Shores or anywhere along the coast, you need a system that can handle the high-volume surges of tourist season without crashing or charging hidden overage fees. You can see how our systems handle these transactions by viewing a live demo of our latest hardware.
The Power of Dual Pricing and Surcharging
One of the most effective ways to manage a payment processing fee is to pass the cost along to the customer. This is known as surcharging or dual pricing. In a surcharging program, a small fee (usually around 3% to 4%) is added only to credit card transactions. Customers who pay with cash or debit do not pay the fee. Dual pricing is slightly different; it presents a "cash price" and a "card price" for every item.
These programs are legal in the United States, but they come with strict rules. You must display clear signage at the entrance and at the point of sale. You also cannot surcharge debit cards, even if they are run as credit. When implemented correctly, these programs can reduce your out-of-pocket processing costs to nearly zero. This is a massive advantage for small businesses operating on thin margins, especially in competitive markets like Alabama.
Dealing with Chargebacks and Disputes
A chargeback occurs when a customer disputes a charge through their bank. Not only do you lose the sale amount, but the processor also charges you a chargeback fee, which can range from $15 to $50 per incident. These fees are separate from your standard payment processing fee. To prevent these, always use EMV-compliant chip readers. If you swipe a chip card instead of dipping it, you lose the "liability shift" and are automatically responsible for any fraud that occurs. High chargeback rates can also lead to your merchant account being flagged as "high-risk," which leads to even higher rates or account termination.
Conclusion: Taking Control of Your Rates
Managing your payment processing fee requires constant vigilance. Rates change, card brands update their rules, and processors often creep their markups higher over time. By understanding the difference between interchange and markup, and by considering options like dual pricing, you can keep more of your hard-earned money. If you are still unsure if you are getting a fair deal, it helps to revisit the basics of how much are card processing fees and compare them to your current statement. Don't let confusing statements hide the profit you deserve.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.