
Fees & Rates
Interchange Fees Debit vs Credit: A Small Business Guide to Processing Costs
Every time a customer swipes a card, you pay a fee that is largely determined by the type of card they use. Understanding the gap between debit and credit costs can save your business thousands of dollars every year.
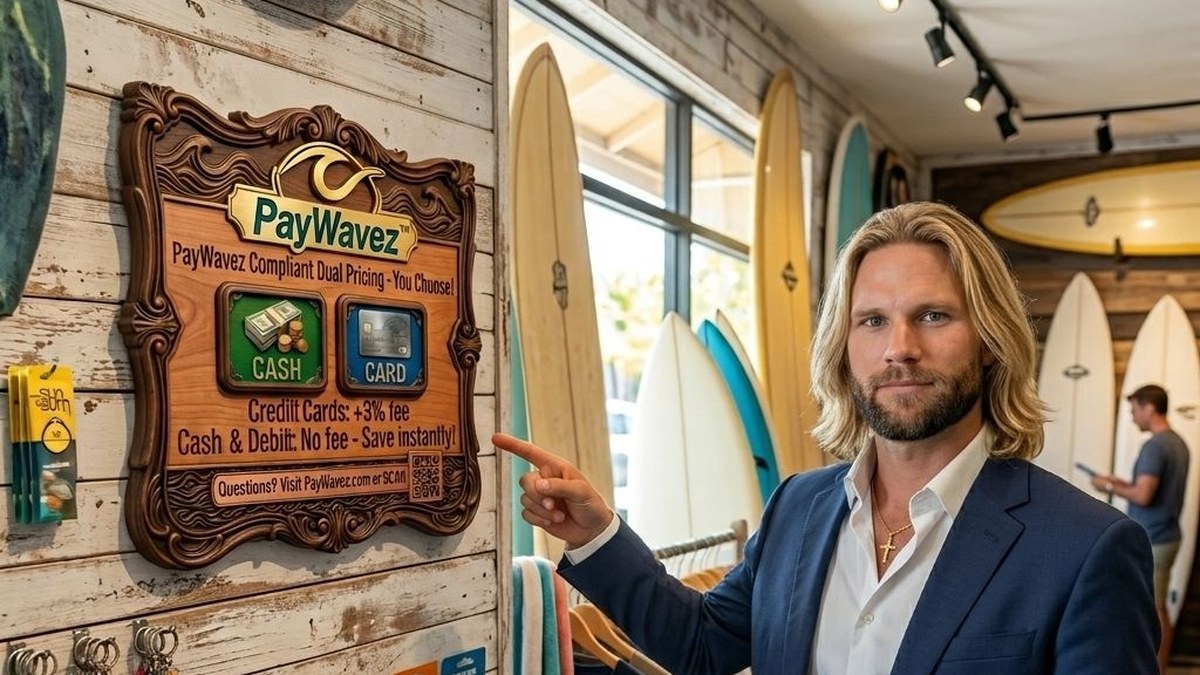
Understanding interchange fees debit vs credit is essential for any small business owner trying to manage their bottom line and keep more of their hard-earned revenue. When you accept a payment, the total fee you see on your merchant statement isn't just one flat charge. It is made up of several layers, the largest of which is the interchange fee. This fee is set by the card networks like Visa and Mastercard and is paid to the bank that issued the customer's card. While these fees might seem like a small percentage, they vary wildly depending on whether your customer uses a debit card or a credit card.
What Are Interchange Fees Anyway?
Interchange fees are the non-negotiable base costs of processing a transaction. They are designed to cover the costs of fraud protection, handling, and the risk the bank takes on when they facilitate a payment. For a small business owner, these fees are the "wholesale" price of credit card processing. Whether you are running a shop in Destin or managing a service fleet, these costs apply to every transaction.
The networks update these rates twice a year, usually in April and October. There are hundreds of different interchange categories. A basic consumer credit card has a different rate than a high-end rewards card, and a corporate card has a different rate than a government-issued debit card. As a merchant, you have no control over which card your customer pulls out of their wallet, but you can control how you manage the costs associated with them.
Interchange Fees Debit vs Credit: Key Differences
The primary difference between debit and credit interchange fees comes down to federal regulation and risk. Debit cards are generally much cheaper for a business to accept because of the Durbin Amendment, a part of the Dodd-Frank Act. This law placed a cap on the interchange fees that large banks can charge for debit transactions. Because the money is coming directly from a customer's checking account, the risk to the bank is lower than it is with a credit transaction where the bank is essentially lending money to the consumer.
Key Statistic: Under the Durbin Amendment, regulated debit card interchange fees are capped at just 0.05% plus $0.21 per transaction for banks with over $10 billion in assets.
Credit card fees, on the other hand, are not capped by federal law. These fees are much higher because they fund the rewards programs, cash back, and travel points that consumers love. When a customer uses a premium rewards card at your business, you are effectively paying for their airline miles through higher interchange fees. Credit cards also carry a higher risk of fraud and chargebacks, which the banks factor into the higher percentage they charge.
Why Credit Card Fees Are So Much Higher
If you look at your merchant statement, you will notice that credit card transactions often cost 2% to 3% or more, while debit transactions might cost less than 1%. This gap exists because credit cards offer a line of credit. The issuing bank is taking a risk that the customer might not pay them back. Additionally, the competition between banks to offer the best rewards means they need higher interchange revenue to stay profitable.
Small business owners often feel the sting of "Interchange Downgrades." This happens when a transaction doesn't meet the security requirements for the lowest possible rate. For example, if you manually key in a credit card number instead of using a modern POS terminal, the risk of fraud increases, and the interchange fee jumps up. This is why having the right hardware is just as important as having the right processing partner.
Every swipe tells a story about your profit margins; knowing the difference between debit and credit costs is the first chapter in taking control of your business.
Regulated vs. Unregulated Debit
Not all debit cards are created equal. The Durbin Amendment only applies to "regulated" banks—those with more than $10 billion in assets (like Chase, BofA, or Wells Fargo). If your customer uses a debit card from a small local credit union or a community bank with fewer assets, that bank is "unregulated." They can charge higher interchange fees than the big banks, though these are still typically lower than credit card rates.
As a business owner, you don't need to know the asset size of every bank in the country. However, you should look for a processor that offers "Interchange Plus" pricing. This pricing model passes the actual cost of the interchange (including the low regulated debit rates) directly to you, with a small, transparent markup. This is much better than "Flat Rate" pricing, where the processor charges you a high flat fee for everything, pocketing the extra savings from those cheap debit swipes.
How to Reduce Your Total Processing Costs
If you feel like you are overpaying, you aren't alone. Many merchants in our Alabama service areas have found that they can significantly reduce their overhead by changing how they handle these fees. One of the most effective ways to combat high credit card interchange is through a Dual Pricing or Surcharging program. These programs allow you to offer a discount to customers who pay with cash or debit, or add a small fee to credit card transactions to cover the cost of the interchange.
Another way to lower costs is to ensure your business is set up with the correct Merchant Category Code (MCC). If your business is misclassified, you could be paying higher interchange rates than necessary. Regularly reviewing your merchant statement to look for hidden fees or unnecessary markups is the best way to ensure your effective rate stays low. If you aren't sure how to read your statement, a professional review can often find hundreds of dollars in monthly savings.
The Role of Your POS System
Your Point of Sale (POS) system plays a huge role in the interchange fees you pay. Modern terminals are designed to capture more data during the transaction. For business-to-business (B2B) sales, providing extra data (known as Level 2 or Level 3 data) can actually lower the interchange rate on corporate credit cards. Older terminals often lack the ability to send this data, costing you money on every sale.
Furthermore, contactless payments and EMV chip technology are more secure than old-fashioned magnetic stripe swipes. By using secure technology, you reduce the risk of chargebacks and help ensure your transactions qualify for the best possible interchange tiers. At PayWavez, we focus on providing small businesses with the tools they need to process payments efficiently and at the lowest possible cost.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.