Fees & Rates
Flat-Rate vs. Interchange-Plus Pricing: Which Actually Costs Less
Flat-rate pricing is easy to understand: one percentage, every transaction, no surprises on the statement. Interchange-plus looks more complicated. For most established businesses processing meaningful volume, it's also the cheaper option -- and the math is simpler than it looks once you know what to compare.
How each model actually works
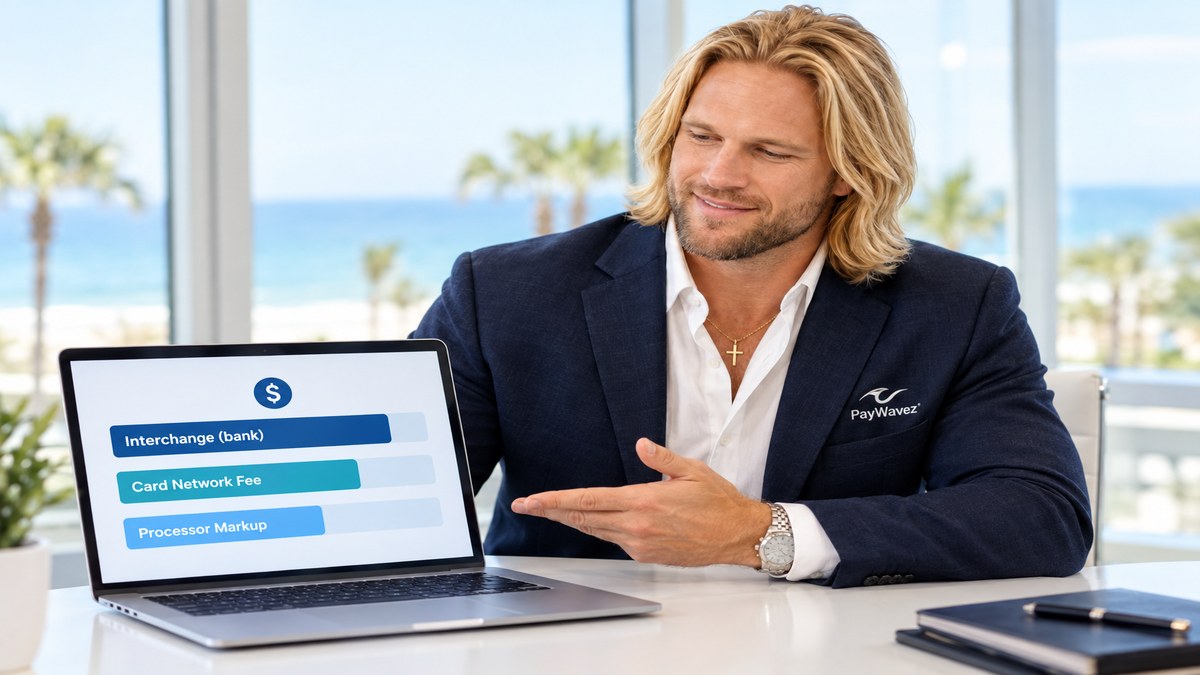
Flat-rate pricing charges one fixed percentage (plus often a small per-transaction fee) on every card transaction, regardless of card type. Interchange-plus pricing passes through the real interchange cost set by the card networks -- which varies by card type, how the card was accepted, and your merchant category -- plus a fixed markup on top. The flat rate is a blended average built to cover the processor's costs across all card types; interchange-plus shows you the real wholesale cost plus a transparent markup.
Why flat-rate can cost more than it looks like
Flat-rate pricing bakes in a cushion above the real interchange cost for every transaction, because the processor is averaging across debit cards, rewards cards, and corporate cards that all have very different real costs. On a debit or basic card transaction -- which carries low real interchange -- a flat rate can mean you're paying well above the wholesale cost. On a premium rewards card, the flat rate might actually be close to or below true cost. The problem is you don't see which is which on a flat-rate statement; it's blended into one number.
- Interchange-plus statements show the real interchange cost and the processor's markup as separate line items, which makes it possible to actually audit what you're paying
- Flat-rate is easiest for very low-volume or highly seasonal businesses that value predictability over squeezing out the lowest possible cost
- Interchange-plus generally rewards businesses with consistent monthly volume and a normal mix of card types
How to actually compare the two for your business
Pull a recent statement and look for two things: what percentage of your transactions are debit versus credit, and whether your current provider shows interchange as a separate line or bundles everything into one rate. If you can't see the interchange line, you can't tell how much markup you're actually paying -- that's the core reason interchange-plus is considered the more transparent model, even though the total dollar figure on the invoice looks more complicated.
Want to see your real numbers side by side?
A free statement review shows what you'd actually pay under each pricing model.