
Fees & Rates
Interchange Fee Cap: What Small Business Owners Need to Know
Understanding the limits on debit card fees can save your business thousands of dollars every year in unnecessary processing costs.
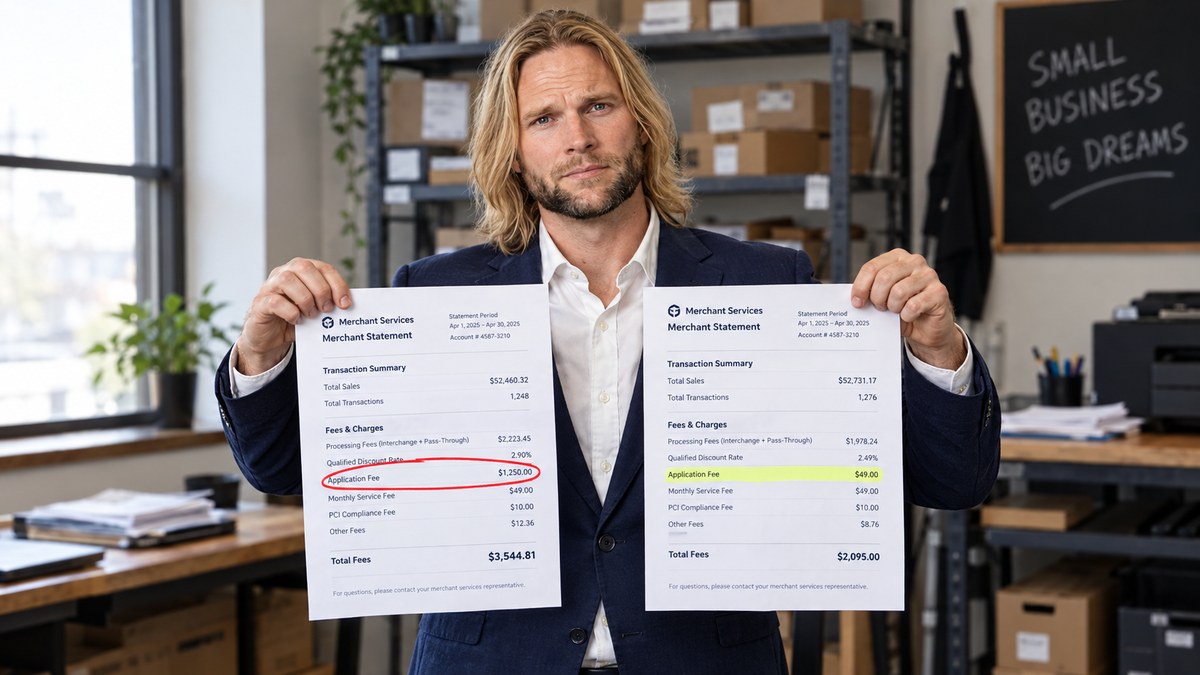
The interchange fee cap is one of the most important regulations for small business owners who want to understand why their debit card processing costs are lower than credit card fees. If you have ever looked at your merchant statement and wondered why some transactions cost pennies while others take a huge bite out of your sale, the answer usually lies in federal regulations. To get a full picture of the basics, you should first read our guide on what are interchange fees on debit cards to see how these costs are structured from the ground up.
What Exactly is the Interchange Fee Cap?
An interchange fee cap is a legal limit on how much a card-issuing bank can charge a merchant for processing a transaction. In the United States, this specifically applies to debit cards issued by very large banks. Before this cap existed, banks could charge whatever they wanted. Merchants had no choice but to pay these fees if they wanted to accept plastic. This put a massive strain on small businesses, especially those with low profit margins like grocery stores or gas stations.
The cap was introduced as part of the Durbin Amendment, which was added to the Dodd-Frank Wall Street Reform and Consumer Protection Act. The goal was simple: stop large banks from overcharging small businesses for the simple act of moving money from a customer's bank account to a business's bank account. Since debit cards are essentially digital checks, the government decided the fees should reflect the actual cost of the transaction rather than being a massive profit center for the banks.
Key Fact: The current interchange fee cap for regulated debit cards is 21 cents plus 0.05% of the transaction value, plus a 1-cent fraud prevention adjustment.
How the Interchange Fee Cap Affects Your Daily Profits
For a small business owner, the interchange fee cap is the reason debit cards are your best friend. When a customer swipes a debit card from a major bank like Chase, Bank of America, or Wells Fargo, the "interchange" portion of your fee is capped. Even if the sale is $100, the bank only gets about 27 cents. Compare that to a rewards credit card, where the bank might take $2.50 or more for the exact same $100 sale.
This massive difference in cost is why many businesses prefer debit over credit. By understanding that this cap exists, you can better predict your monthly expenses. If your customer base primarily uses debit cards, your "effective rate" (the total percentage you pay in fees) should be significantly lower than a business that mostly takes premium credit cards. If you aren't seeing these savings on your statement, it might be time to see a live demo of how transparent pricing should look.
"The interchange fee cap isn't just a legal technicality; it is a shield for small business owners against the rising costs of the modern banking system."
Regulated vs. Unregulated Banks: The $10 Billion Rule
It is a common mistake to think the interchange fee cap applies to every single debit card. It does not. The law only applies to "regulated" banks. A regulated bank is one that has more than $10 billion in assets. This includes all the big national names you see on every street corner. Because these banks handle the vast majority of card transactions in the U.S., the cap covers a huge portion of the market.
However, small community banks and local credit unions are "unregulated." This means they can still charge higher interchange rates for their debit cards. The logic behind this was to protect small banks from losing too much revenue. As a merchant, this means you will still see some debit transactions that cost more than others. When you look at your processing report, you might see some transactions labeled as "Regulated" and others as "Exempt." The exempt ones are the ones from the smaller banks where the cap doesn't apply.
The 2026 Outlook: Are Fees Going Lower?
The world of payments never stays still. Recently, there has been a lot of talk about lowering the interchange fee cap even further. The Federal Reserve has proposed a plan to drop the base fee from 21 cents down to 14.4 cents. This would be a massive win for small businesses. For a business doing thousands of transactions a month, saving 6 or 7 cents on every single debit swipe adds up to real money that can be used for payroll, inventory, or marketing.
While the big banks are fighting these changes, the trend is moving toward more transparency and lower costs for merchants. At PayWavez, we keep a close eye on these regulations to ensure our clients are always getting the benefit of any new caps. Whether you are operating in a busy metro area or looking for Alabama payment processing solutions, staying informed about these changes is the first step to lowering your overhead.
How to Spot the Cap on Your Merchant Statement
If you are on an "Interchange Plus" pricing plan, spotting the interchange fee cap is easy. You will see a line item for debit transactions that shows the 21-cent fee. This is the most transparent way to process payments. However, if you are on a "Flat Rate" or "Tiered" plan, your processor might be pocketing the savings from the cap instead of passing them to you.
For example, if your processor charges you a flat 2.6% + 10 cents for every transaction, they are making a huge profit when a customer uses a capped debit card. The bank only charges the processor about 27 cents for a $100 debit sale, but the processor charges you $2.70. They keep the difference. This is why we often recommend merchants in places like Gulf Shores look closely at their statements to ensure they are actually receiving the benefits of the federal cap.
Maximizing Your Savings Beyond the Cap
While the interchange fee cap helps with debit cards, it doesn't do anything for credit card fees. To truly lower your costs, you have to look at other strategies like dual pricing or surcharging. These programs allow you to offer a cash discount to customers who pay with cash or a check, or to add a small service fee to credit card transactions to cover the processing costs.
When you combine the low cost of capped debit transactions with a smart surcharging program, you can get your total processing bill close to zero. This is the ultimate goal for any small business owner. By understanding the rules, you can stop being a victim of high fees and start taking control of your revenue. Regulation is there to help, but you have to work with a processor that actually implements these rules fairly.
Conclusion
The interchange fee cap is a powerful tool for small business owners. It keeps debit card costs predictable and prevents large banks from taking an unfair share of your hard-earned money. By knowing the difference between regulated and unregulated banks and checking your statement for proper pricing, you can save thousands. Don't forget to revisit our detailed breakdown of what are interchange fees on debit cards to make sure you have the full context of how these fees work for your business.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.