
Fees & Rates
How to Interchange Fees Work: The Small Business Owner’s Guide
Understanding the backbone of credit card processing costs is the first step toward lowering your monthly merchant statement and keeping more of your hard-earned revenue.
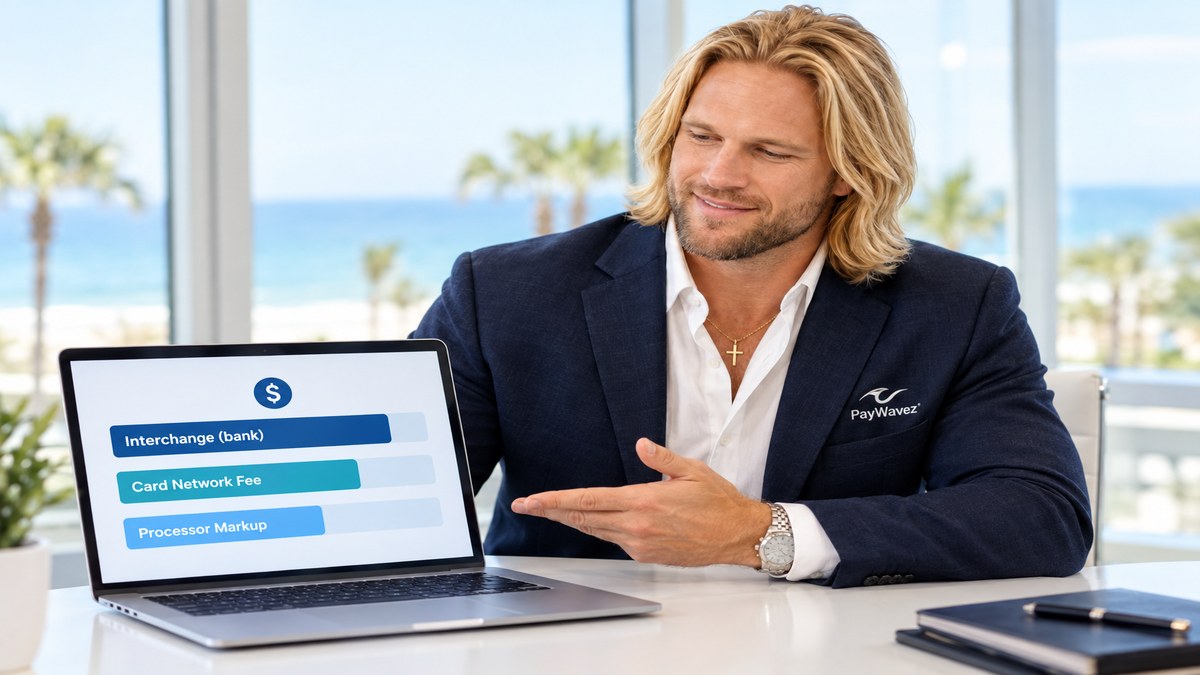
If you have ever looked at your monthly merchant statement and felt confused, you are probably wondering how to interchange fees work for your business. For most small business owners, credit card processing fees feel like a black box. You see money leaving your account every month, but it is not always clear where that money goes. Interchange is the largest part of that cost, and understanding it is vital if you want to manage your overhead effectively.
How to interchange fees work behind the scenes
Interchange fees are the base rates set by the card networks, such as Visa, Mastercard, Discover, and American Express. These are not fees charged by your credit card processor. Instead, they are the fees that your bank (the acquiring bank) must pay to the customer's bank (the issuing bank) every time a transaction occurs. The card networks act as the middleman, setting these rates twice a year, usually in April and October.
Think of interchange as the wholesale cost of accepting a credit card. Just like a retail store buys inventory at a wholesale price and sells it at a retail price, your payment processor takes the interchange rate and adds a small markup to cover their own costs and profit. Because these rates are set by the networks, they are the same for every processor. No processor can get a "special deal" on interchange; it is a level playing field at the base level.
Interchange fees typically account for 70% to 90% of the total fees a small business pays to accept credit cards.
The Three Parts of Your Processing Fee
When you see a total fee on your statement, it is actually made up of three distinct parts. First is the interchange fee we are discussing. Second are assessment fees, which go directly to the card networks (Visa/Mastercard) to pay for the operation of their networks. Third is the processor markup. This third part is the only portion that is actually negotiable. If you want to see how these fees look on a modern system, you can view our live demo to see transparent reporting in action.
Factors That Determine Your Interchange Rate
Not every transaction costs the same. There are hundreds of different interchange categories, and the rate for a specific sale depends on several factors. Understanding these can help you change your business habits to save money.
- Card Type: Basic debit cards have the lowest interchange rates because they carry the least risk. On the other hand, premium rewards cards and corporate cards have much higher rates. The banks use these higher fees to fund the points and travel perks they give to the cardholders.
- Entry Method: How you take the payment matters. Transactions where the card is physically present (swiped, dipped, or tapped) are considered lower risk. Transactions where the card is not present, such as online orders or over-the-phone payments, have higher interchange rates because the risk of fraud is greater.
- Business Type: The card networks assign a Merchant Category Code (MCC) to your business. A grocery store might have a different interchange rate than a high-end jewelry shop or a seasonal business on the coast.
Interchange isn't a fee from your processor; it's the cost of entry to the card network that every merchant must pay.
Interchange-Plus vs. Flat-Rate Pricing
How your processor bills you for interchange makes a huge difference. Many popular "easy" processors use flat-rate pricing. They charge you one set percentage (like 2.9% + 30 cents) regardless of the actual interchange cost. While this is simple, it is often the most expensive way to process payments because the processor pockets the difference when a low-cost debit card is used.
Interchange-plus pricing is more transparent. With this model, the processor passes the exact interchange cost through to you and adds a small, fixed markup. This allows you to benefit from lower rates on debit cards and basic credit cards. For businesses with higher volume, interchange-plus is almost always the more affordable option. We help businesses across the region transition to these fairer models, from our Alabama payment processing hub to local shops needing Destin credit card processing.
How to Reduce Your Total Processing Costs
While you cannot negotiate the interchange rates themselves, you can take steps to ensure you are paying the lowest possible version of those rates. This is often called "interchange optimization."
Use Modern Terminals
Using an EMV chip terminal or a contactless tap-to-pay system reduces the risk of fraud. When you use modern hardware, you qualify for lower interchange tiers. If you are still swiping the old-fashioned magnetic stripe, you are likely paying a penalty rate on every single transaction.
Ensure PCI Compliance
Many business owners ignore their PCI compliance paperwork. If you are not compliant, your processor might hit you with monthly non-compliance fees. More importantly, being compliant helps you avoid certain "downgrades" where the card networks charge you more because they view your business as a security risk.
Consider Dual Pricing
One of the most effective ways to manage interchange costs is to stop paying them entirely. Dual pricing programs allow you to offer a cash price and a card price to your customers. The card price includes the cost of the interchange and processing fees. This allows you to keep 100% of your sale price while still giving customers the convenience of using their cards. This is a legal and transparent way to protect your margins.
The Importance of Statement Reviews
The best way to figure out if you are paying too much is to have a professional look at your merchant statement. Many processors hide their markups inside complicated categories or "bundled" rates. A transparent provider will break down every interchange fee so you can see exactly what the banks are charging versus what the processor is taking.
By understanding the mechanics of these fees, you move from being a frustrated bystander to an informed business owner. You can choose hardware and software that prioritizes low rates and security, ensuring that your business stays profitable for years to come.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.