
Payment Technology
Choosing the Right Enterprise Payment Gateway for Your Growing Business
Scaling your business requires more than just a simple card reader; it demands a robust enterprise payment gateway that handles high volume without eating your margins.
Finding the right enterprise payment gateway is the most critical step for any business owner looking to scale their operations without losing a fortune to hidden fees. As your business grows from a single storefront to a multi-location operation or a high-volume online store, the way you handle credit card processing must evolve. A basic setup that worked when you were doing $5,000 a month will likely become a bottleneck—and a massive expense—when you hit $50,000 or $500,000 in monthly sales.
What Exactly is an Enterprise Payment Gateway?
At its core, a gateway is the digital tunnel that connects your business to the banking networks. When a customer swipes a card at your terminal or enters their details on your website, the gateway encrypts that data and sends it off for approval. An enterprise-level version of this tool is built for speed, security, and complex routing. It isn't just about making the light turn green on the terminal; it is about managing thousands of transactions simultaneously while keeping your data safe from hackers.
For small business owners in the US, the gateway is often bundled with your merchant account. However, as you grow, you might find that separate gateway providers offer better features, such as advanced reporting or the ability to route transactions to different banks to save on fees. This flexibility is what separates a standard small business tool from a true enterprise solution.
Key Insight: Businesses that switch from flat-rate processing to an enterprise gateway with interchange-plus pricing often save between 0.5% and 1.2% on every single transaction.
The Reality of Processing Fees at Scale
When you are small, flat-rate pricing (like 2.9% + 30 cents) sounds simple and fair. But for an enterprise-level business, that simplicity is incredibly expensive. You need to understand the three main components of your fees: interchange, assessment, and the processor's markup. Interchange fees are set by the card brands (Visa, Mastercard) and are non-negotiable. However, the markup added by your gateway provider is where you have room to move.
An enterprise payment gateway should allow you to see exactly what you are paying for. This is often called "Interchange Plus" pricing. It means you pay the raw cost of the transaction plus a small, transparent fee to the provider. This transparency prevents "fee creep," where processors slowly raise their rates over time without you noticing. If you are operating a business in a high-traffic area like Pensacola, these fractions of a percent can add up to thousands of dollars in savings every year.
"The biggest mistake high-volume merchants make is prioritizing a 'simple' fee structure over a transparent one. Transparency is where the real profit stays in your pocket."
Why Your Enterprise Payment Gateway Needs Surcharge Support
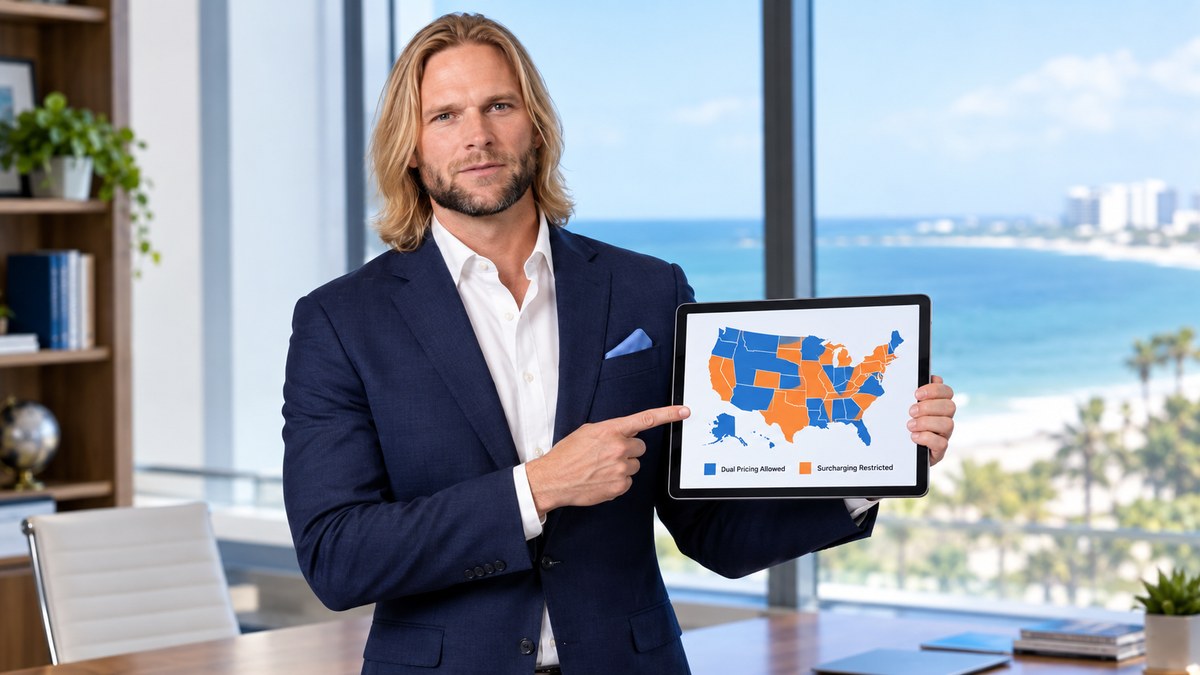
One of the most effective ways to protect your margins is through surcharging or cash discount programs. These programs allow you to pass the cost of credit card processing directly to the customer who chooses the convenience of plastic, while offering a lower price to those who pay with cash. Not every gateway is equipped to handle this legally and technically.
A proper enterprise payment gateway will automatically calculate the correct surcharge amount, ensure it doesn't exceed legal limits (usually capped at 3%), and print the required notification on the receipt. This keeps you compliant with both state laws and card brand rules. For businesses across the Southeast, from our Alabama payment processing hubs to Florida, staying on the right side of these rules is vital to avoiding heavy fines from Visa or Mastercard.
Merchant Accounts vs. Payment Aggregators
Many new business owners start with aggregators like Square or PayPal. These companies lump thousands of businesses into one giant merchant account. While easy to set up, they are notorious for freezing accounts or holding funds without warning if they see a sudden spike in your sales. An enterprise business cannot afford to have its cash flow cut off for 48 hours because of a "security review."
Instead, you need your own dedicated merchant account. This is a private bank account specifically for your card sales. When you pair a dedicated merchant account with a high-quality gateway, you get faster funding (often next-day), higher processing limits, and a real human being to call when something goes wrong. You aren't just a number in a database; you are a valued client with a contract that protects your right to get paid.
Managing Chargebacks and Fraud at the Enterprise Level
As your volume increases, so does your risk of chargebacks. A chargeback happens when a customer disputes a charge with their bank instead of asking you for a refund. If you don't have the right tools, these can become a nightmare. An enterprise payment gateway includes fraud filters that can block suspicious transactions before they even happen. They use "velocity checks" to see if the same card is being used too many times in a short window, or "geographic blocks" to stop orders from high-risk areas.
When a dispute does happen, your gateway should provide a clear portal to upload your evidence. Proving that a customer received their goods or services is much easier when your gateway stores digital receipts, IP addresses, and delivery confirmations all in one place. Effective chargeback management can save an enterprise business tens of thousands of dollars in lost inventory and bank penalties.
Integrating Terminals and POS Systems
Your gateway shouldn't just live in the cloud; it needs to talk to your physical hardware. Whether you are using a smart terminal at a checkout counter or a full POS system in a restaurant, the integration must be seamless. This is known as "omnichannel" processing. It means your online sales and your in-person sales all flow into the same reporting dashboard.
Modern enterprise gateways support EMV (chip) technology and contactless payments like Apple Pay and Google Pay. They also allow for "tokenization," which is a fancy way of saying they store customer card data in a secure, unhackable format. This allows your regular customers to pay with one click without you ever having to see or store their actual credit card number, which significantly reduces your PCI compliance burden.
How to Switch Without Losing a Single Sale
The biggest fear business owners have is that switching their gateway will cause downtime. They worry that their website will go dark or their terminals will stop working. However, a professional transition is handled in parallel. You set up your new enterprise payment gateway and merchant account while your old one is still active. You test the connection, train your staff on the new terminals, and only "flip the switch" once you know everything is perfect.
At PayWavez, we specialize in making this transition invisible to your customers. We help you audit your current statements to find the hidden fees and then build a custom solution that fits your specific industry. If you are ready to see the difference a pro-grade system makes, you can view a live demo of our platform today.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.