Fees & Rates
Credit Card Processing Fees Charged to Customers: What You Need to Know
Many small business owners are looking for ways to offset rising costs by passing credit card fees to their customers. This guide explains the legal rules, state laws, and best practices for implementing a surcharge or dual pricing program.
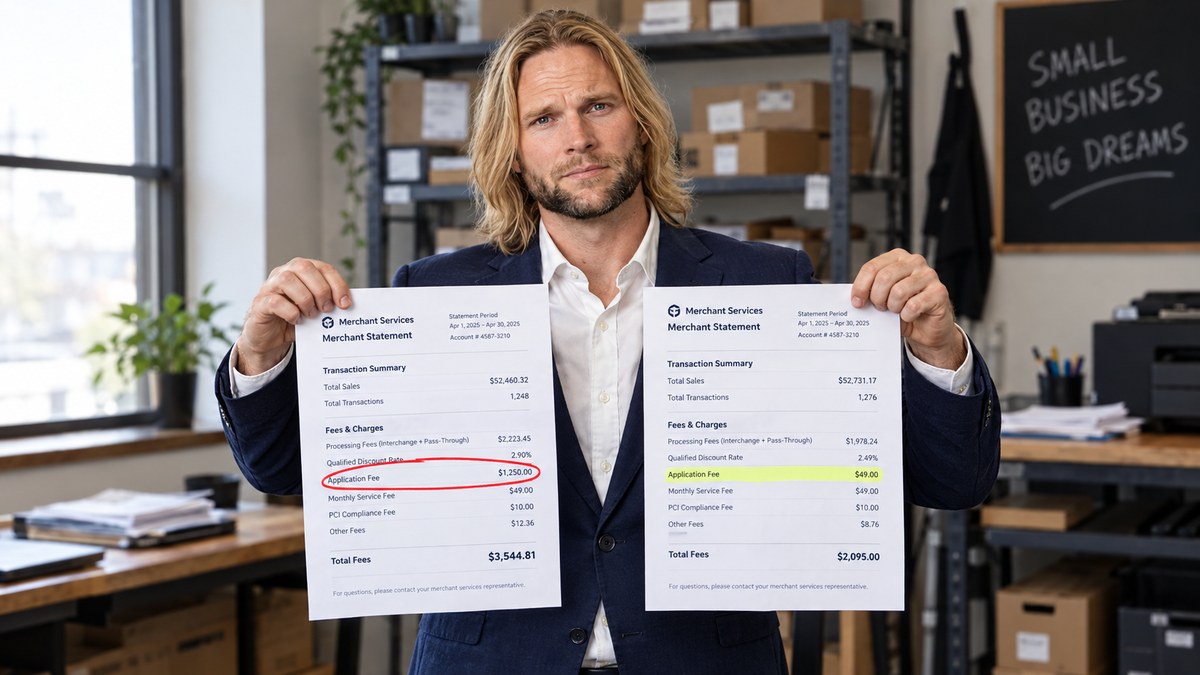
Credit card processing fees charged to customers are a hot topic for small business owners looking to protect their profit margins. As costs for labor, rent, and inventory continue to rise, the 3% to 4% lost to merchant service fees can be the difference between a profitable month and a loss. Fortunately, modern payment technology and shifting legal landscapes have made it easier for businesses to share these costs with the people using the cards. However, you cannot simply add a fee to a receipt without following specific rules set by both the government and the major card brands like Visa and Mastercard.
Understanding Credit Card Processing Fees Charged to Customers
When we talk about credit card processing fees charged to customers, we are usually referring to one of three programs: surcharging, cash discounting, or dual pricing. Each of these has a slightly different legal definition and set of requirements. Surcharging is the most direct method; it involves adding a percentage-based fee to a credit card transaction at the point of sale. This fee is meant to cover the cost that the merchant pays to the processor. It is important to note that you can only apply these fees to credit cards, never to debit cards or prepaid cards.
Many business owners prefer these programs because they allow the business to keep 100% of the sale price. If you sell a product for $100, and the processing fee is $3.50, a traditional setup means you only keep $96.50. By passing that fee along, you keep the full $100. To see how this looks in action, you can view our live demo of a terminal setup that handles these calculations automatically.
According to industry data, small businesses that implement a dual pricing or surcharge program see an immediate increase in net profit of 2.5% to 3.8% without a significant loss in customer volume.
Is It Legal to Pass Fees to Your Customers?
The short answer is yes, but the long answer depends on where you live and how you do it. For many years, card brands had strict rules against surcharging. However, following several class-action lawsuits and changes in state legislation, the practice has become legal in the vast majority of the United States. As of 2026, only a handful of states have active restrictions or specific requirements that make traditional surcharging difficult.
Even in states with stricter rules, "Dual Pricing" is almost always a legal alternative. Dual pricing simply means showing two prices for every item: a card price and a cash price. This is seen as a price difference rather than a penalty for using a card, which makes it much more acceptable under various state consumer protection laws. If you are operating in the South, you should check our Alabama payment processing hub for specific regional insights into how these laws are applied locally.
"Passing the fee isn't just about saving money; it's about being transparent with your customers about the cost of doing business in a digital world."
Legality of Credit Card Processing Fees Charged to Customers
When implementing credit card processing fees charged to customers, you must comply with the rules set by the card networks (Visa, Mastercard, Discover, and American Express). These rules are designed to ensure that the customer is not surprised by the fee at the end of the transaction. First, you must notify the card brands at least 30 days before you begin surcharging. Second, the fee you charge cannot exceed your actual cost of processing, and it is strictly capped at 3% (or 4% in some specific older agreements, though 3% is the modern standard for many networks).
Furthermore, you must provide clear signage at the entrance of your store and at the point of sale. This signage must inform customers that a fee will be applied to credit card transactions. Your receipts must also show the surcharge as a separate line item. This transparency is key to staying compliant and keeping your merchant account in good standing. Failure to follow these rules can result in heavy fines or even the termination of your ability to accept cards.
The "No Debit Card" Rule You Must Follow
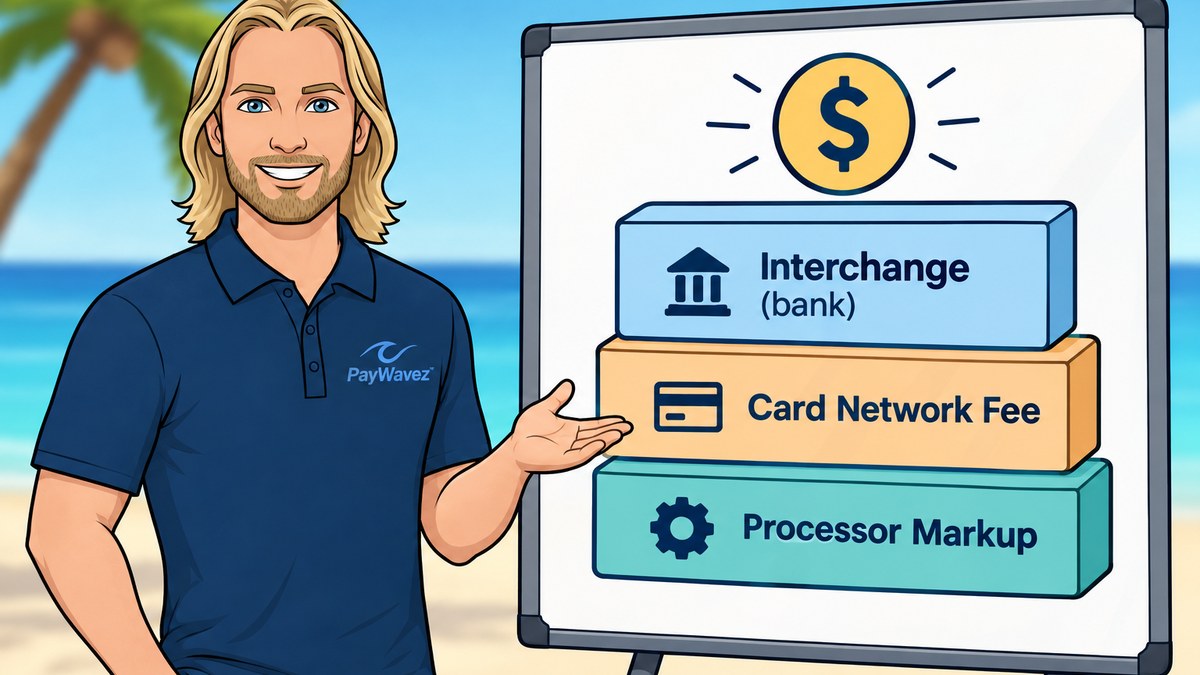
One of the biggest mistakes business owners make is trying to apply credit card processing fees charged to customers to debit card transactions. Under the Durbin Amendment of the Dodd-Frank Act, it is illegal to surcharge a debit card, even if the customer chooses to run it as "credit" (without a PIN). This is because debit cards have significantly lower interchange rates than credit cards, and the law protects consumers from being overcharged for using their own banked funds.
If your POS system is not smart enough to distinguish between a credit card and a debit card, you could be at risk of a legal violation. This is why working with a provider like PayWavez is essential. Our systems automatically detect the card type and only apply the fee when it is legally allowed. For businesses on the coast, such as those looking for Destin credit card processing, having a system that handles these nuances is vital during the busy tourist season when transaction volume is high.
State Laws and Regional Differences
While federal law and card brand rules provide a baseline, state laws can add another layer of complexity. For example, states like New York and Maine have historically required that the "total price" including the credit card fee be the most prominent price shown. This has led many merchants in those states to move away from surcharging and toward a dual pricing model, where the sticker on the shelf shows both the cash and card prices clearly.
In the Gulf Coast region, laws are generally merchant-friendly, but you still need to be aware of how local consumer protection offices view these fees. Providing clear, easy-to-read signage is the best way to avoid complaints. Most customers are now accustomed to seeing these fees at gas stations and small restaurants, so as long as you are honest and upfront, they are usually happy to support a local business by paying the small fee or choosing to pay with cash.
Required Signage and Customer Notification
To stay compliant, you need three main types of communication. First, a sign at the door or entrance that states you charge a fee for credit card use. Second, a sign at the register or on your website's checkout page that explains the exact percentage of the fee. Third, the fee must appear on the printed or digital receipt as its own line item, clearly labeled as a "Surcharge" or "Credit Card Fee."
Many merchants worry that these signs will drive customers away. In reality, most small business owners find that customers are very understanding when the reason for the fee is explained. You can even use the signage as an opportunity to explain that by passing the fee, you are able to keep your base prices lower for everyone, rather than raising prices across the board to cover processing costs.
How to Implement a Zero-Fee Program with PayWavez
Setting up credit card processing fees charged to customers doesn't have to be a manual headache. PayWavez specializes in helping small businesses transition to a dual pricing or surcharge model that is 100% compliant and automated. We provide the hardware, the software, and the required signage to make the switch seamless. Our terminals are pre-programmed to identify debit cards and exempt them from fees, ensuring you never break the law by accident.
If you are tired of seeing your hard-earned profits disappear into the pockets of big banks, it's time to consider a change. We can review your current merchant statement and show you exactly how much you would save by switching to a program where the fees are covered by the transaction itself. Most of our clients save thousands of dollars per year, which can be reinvested back into the business for growth, hiring, or equipment upgrades.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.