
Payments 101
How a Commercial Payment System Works for Your Business
A commercial payment system is more than just a card reader; it is the entire digital pipeline that moves money from your customer’s bank to yours.
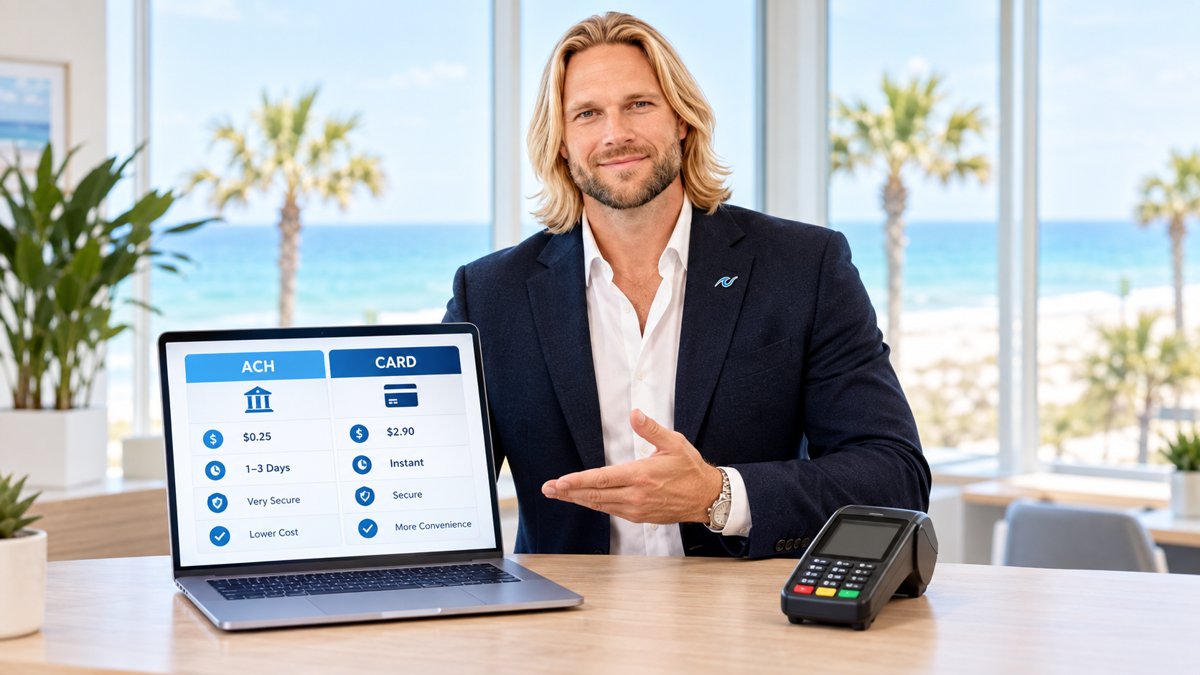
When you hear the term commercial payment system, it is easy to get lost in the jargon. At its simplest level, this system is the collection of tools and services that allow a business to accept non-cash payments. Whether you are running a retail shop in Mobile, Alabama, or managing a high-volume online store, understanding this infrastructure is key to controlling your costs. For a deeper look at the technical side, you can also check out our full commercial payment systems guide.
The Four Pillars of a Payment System
Every commercial payment system relies on four main components working together in seconds. If any one of these is missing or poorly configured, your business can face delays, high fees, or security risks.
- The Merchant Account: This is a special type of bank account that allows you to accept credit and debit card payments. It acts as a staging area before funds are moved to your regular business checking account.
- The Payment Gateway: This is the digital bridge. It securely sends transaction data from the point of sale to the processing network.
- The Processor: This is the company (like PayWavez) that handles the actual communication between the banks to approve or decline a sale.
- Hardware and Software: This is the physical card reader or the online checkout page where the customer actually provides their payment info.
According to the Federal Reserve, card payments now account for over 75% of all non-cash transactions in the United States, making a reliable payment system a non-negotiable for business growth.
Why Processing Models Matter
Not all systems are priced the same way. Most small businesses start with "flat-rate" processing because it looks simple. However, as your business grows, flat rates often become the most expensive way to get paid. Many established businesses prefer "interchange-plus" pricing, which separates the actual bank costs from the processor's markup, providing much more transparency.
One of the most effective ways to lower your overhead is through a Dual Pricing program. This tool allows you to offer a lower price for cash payments while the card processing costs are covered by the customer at the point of sale. It is a game-changer for businesses looking to eliminate monthly processing bills entirely.
The best payment system isn't the one with the most features; it's the one that lets you keep more of your own hard-earned money at the end of the day.
Choosing the Right System for Your Business
The right setup depends entirely on how you interact with your customers. Use this table to see where you fit:
| Business Type | Recommended Hardware | Key Feature Needed |
|---|---|---|
| Retail / Restaurant | Smart Countertop Terminal | Fast checkout & tip management |
| Field Services | Mobile Bluetooth Reader | Offline processing & rugged build |
| E-commerce | Virtual Terminal / API | Fraud protection & recurring billing |
| Professional Services | Invoicing Software | ACH and card-on-file options |
If you want to see how these systems look in action, you can view a live demo of our latest hardware and software integrations. We also provide specialized support through our Alabama payment processing hub for local businesses needing hands-on help.
Security and Compliance
Every commercial payment system must follow PCI-DSS (Payment Card Industry Data Security Standard) rules. This ensures that customer data is encrypted and protected from hackers. When choosing a system, always ask if the hardware is EMV-compliant (chip-ready) and if the software uses tokenization to hide sensitive card numbers.
Switching to a modern system doesn't have to be a headache. Most businesses can upgrade their hardware and lower their rates in less than a week. For a comprehensive review of your current setup, refer back to our commercial payment systems guide to ensure you aren't missing any key features.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.