
Banking Infrastructure
How to Choose the Best Issuer Processor for a New Rewards Credit Card
Selecting an issuer processor is the most critical infrastructure decision a bank makes when launching a rewards card, balancing modern API flexibility with strict banking compliance.
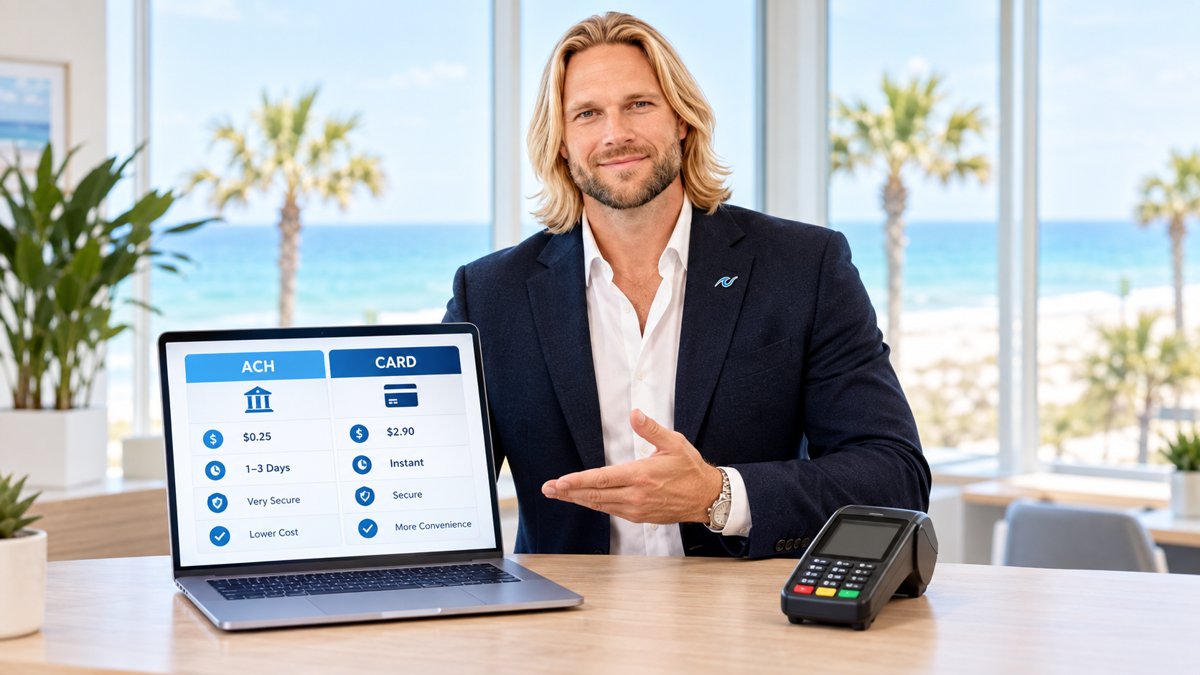
When a bank or credit union decides to launch a new rewards credit card, the technical backbone of that program is the issuer processor. Unlike a merchant processor—which helps businesses accept payments—an issuer processor is the "brain" behind the card itself. It manages the cardholder's balance, authorizes transactions in real-time, and tracks the rewards points that keep customers loyal.
Choosing the right partner is a high-stakes decision. If the processor is too rigid, you won't be able to offer the creative rewards structures that modern consumers expect. If they are too "lite" on compliance, you risk running afoul of banking regulations. While you evaluate these back-end systems, it is also helpful to understand how the other side of the counter works. For example, seeing how the best card processing companies for restaurants handle transactions can give you insight into the merchant experience your cardholders will encounter.
The Two Paths: Legacy vs. Modern Cloud Processing
The market for issuer processors is generally split into two camps: legacy giants and modern fintech-first platforms. Understanding which path fits your bank’s culture and technical capability is the first step.
Legacy Processors (FIS, Fiserv, TSYS)
These companies have been around for decades. They power the majority of the world’s largest banks. Their strength lies in their massive scale and deep experience with regulatory hurdles. However, they are often built on older mainframe technology. This can make it slow and expensive to launch new features or integrate with modern mobile apps.
Modern API-First Processors (Marqeta, Galileo, i2c, Lithic)
These platforms were built for the cloud era. They offer "API-first" architectures, meaning your developers can build custom card experiences much faster. These are often the best choice for banks that want to launch a highly customized rewards program with real-time notifications and instant virtual card issuance.
The Rewards Engine: The Heart of Your Program
Since you are launching a rewards card, the "Rewards Engine" is your most important feature. Some processors have this built-in, while others require you to plug in a third-party rewards provider. You need to verify that the processor can handle:
- Real-time Point Accrual: Can the customer see their points balance update the moment they swipe?
- Tiered Rewards: Can you easily change point multipliers for specific categories like gas, groceries, or travel?
- Redemption Flexibility: Does the system support statement credits, gift cards, and direct travel bookings?
A rewards card is only as good as the ledger behind it. If your processor cannot handle complex, real-time point calculations, your customer experience will quickly fall behind the competition.
Balancing the Ecosystem
As a bank, you are providing the capital and the card, but the ecosystem only works if merchants can afford to accept your rewards card. High-reward cards often come with higher interchange fees for the business owner. To see how merchants manage these costs, many look toward programs like PayWavez Dual Pricing. This allows businesses to maintain their margins while still welcoming your bank's premium cardholders. Understanding this balance helps you design a card that is both attractive to users and sustainable for the payment network.
Technical Checklist for Bank Stakeholders
Before signing a multi-year contract with an issuer processor, your technical and product teams should verify these four items:
- Ledger Accuracy: Does the processor provide a true system of record that meets all auditing requirements?
- Fraud Tools: What level of machine learning is applied to transaction monitoring to prevent unauthorized spend?
- Card Fulfillment: Do they handle the physical printing and mailing of cards, or do you need a separate partner?
- Sandbox Environment: Can your developers test the full lifecycle of a transaction before you go live?
If you are still in the early stages of planning your payment strategy, you can see a live demo of modern payment interfaces to understand the user experience side of the industry. For banks operating in specific regions, such as our partners in the Alabama payment processing hub, local support and understanding regional spending patterns can also be a significant advantage.
Ultimately, the best issuer processor is the one that aligns with your bank's speed of innovation. If you want a "set it and forget it" card, a legacy player is safe. If you want to compete with the latest fintech apps, a modern API-driven processor is the clear winner. By understanding the merchant side—including how the best credit card processing companies for restaurants operate—you can build a card program that thrives in the real world.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.