
Fees & Rates
Cheap Credit Card Processing No Monthly Fee: The Small Business Guide
Stop paying for your merchant account just to have it open. Learn how to find a processor that only charges you when you actually make a sale.
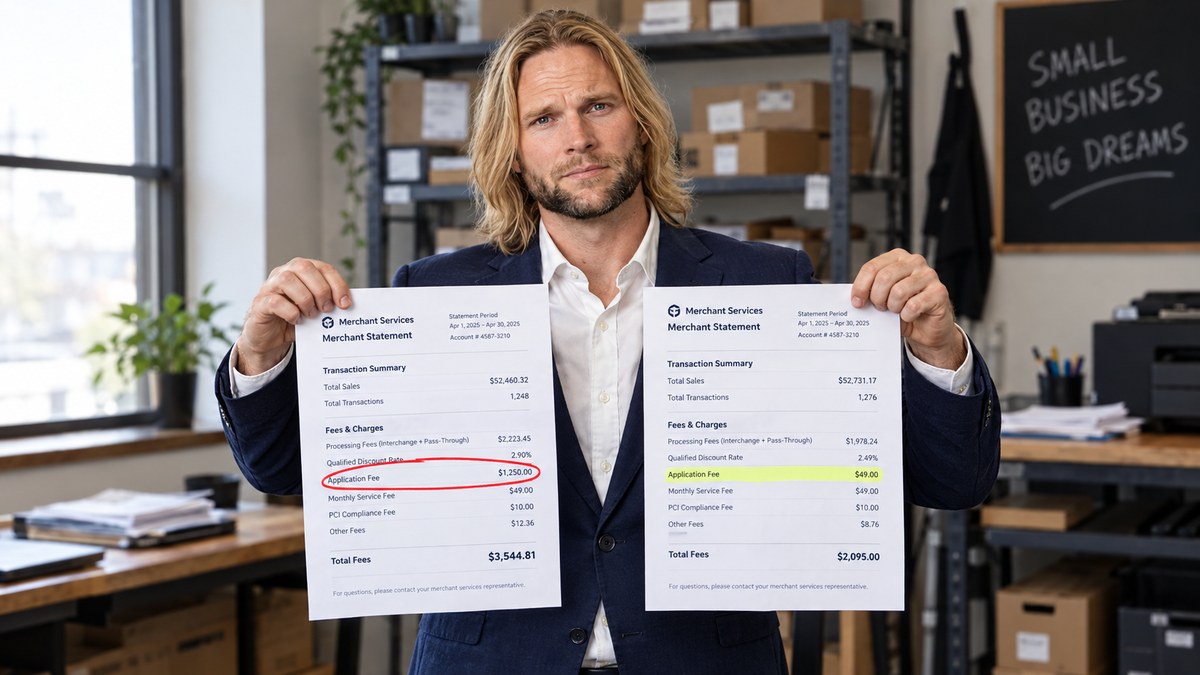
Cheap credit card processing no monthly fee is a top priority for small business owners looking to maximize their margins. When you are just starting out or running a seasonal business, every dollar counts. Traditional merchant accounts often come with a long list of recurring costs. You might see statement fees, PCI compliance fees, and monthly maintenance fees that add up to $30 or $50 before you even swipe a single card. For a low-volume business, these fixed costs can eat up a huge percentage of your profits. Finding a provider that offers a pay-as-you-go model allows you to keep your overhead low and only pay for the services you actually use.
Why Monthly Fees Exist (and Why You Should Avoid Them)
Many traditional banks and large processors charge monthly fees to cover the cost of maintaining your account and providing customer support. They view these fees as a way to ensure a steady stream of revenue, even if your business has a slow month. However, for many small businesses, these fees are unnecessary. Modern payment technology has made it much easier for processors to manage accounts without high overhead. If you are a small retailer, a mobile service provider, or a seasonal shop in a place like Pensacola, you should not be penalized for having a quiet month. Avoiding monthly fees means your processing costs scale directly with your sales volume.
The Trap of the "Free" Terminal
Sometimes, a processor will offer you a "free" credit card terminal but then charge a high monthly fee to cover the cost of the hardware over time. This is often a lease in disguise. It is usually much cheaper in the long run to buy your equipment upfront or choose a processor that offers affordable mobile readers. Always look at the total cost of ownership, not just the upfront price of the hardware. A cheap credit card processing no monthly fee plan is only truly cheap if the transaction rates are also competitive.
According to industry data, small businesses can save an average of $300 to $600 per year simply by switching from a traditional monthly-fee merchant account to a pay-as-you-go provider.
Comparing Top Providers for Cheap Credit Card Processing No Monthly Fee
When searching for the best deal, you will likely encounter names like Square, PayPal, and PayWavez. These companies are popular because they do not charge a monthly subscription fee for their basic processing services. Instead, they charge a flat percentage plus a small per-transaction fee. This model is very transparent. You know exactly what you will pay for every dollar you process. For example, if your rate is 2.6% + $0.10, and you don't sell anything all month, your bill is $0. This flexibility is vital for businesses with fluctuating sales or those that primarily operate during peak tourist seasons.
However, flat-rate pricing is not always the cheapest option as your volume grows. Once you are processing more than $5,000 or $10,000 a month, the fixed percentage can become more expensive than an interchange-plus model. PayWavez offers a unique middle ground by providing transparent pricing structures that can include dual-pricing or surcharging options. These programs allow you to pass the processing costs on to the customer, effectively bringing your monthly processing bill down to nearly zero, regardless of your volume.
The Difference Between Flat-Rate and Interchange-Plus
To find the most affordable option, you need to understand the two main pricing structures. Flat-rate pricing is simple: one rate for every card type. Whether a customer uses a basic debit card or a high-rewards credit card, you pay the same percentage. This is great for predictability and is common among no-monthly-fee providers. Interchange-plus pricing, on the other hand, is more transparent. You pay the actual cost set by the card networks (Visa, Mastercard) plus a small markup for the processor. While this often requires a monthly fee, the lower transaction rates can save you more money if you have high volume.
Which One Should You Choose?
If you are looking for cheap credit card processing no monthly fee, you are likely in the flat-rate category. This is the best choice for businesses processing less than $3,000 per month. It keeps things simple and ensures you aren't paying for an account you aren't using. If you want to see how these rates impact your specific business, you can check out a live demo of how modern POS systems handle these transactions in real-time. Seeing the breakdown of a sale can help you visualize where your money is going.
Transparency in payment processing isn't just about the rate you pay; it's about knowing exactly what is leaving your bank account every month without any surprises.
How Surcharging and Cash Discounts Eliminate Your Costs
One of the most effective ways to achieve cheap credit card processing no monthly fee is to implement a surcharging or cash discount program. Surcharging allows you to add a small fee (usually around 3% to 4%) to every credit card transaction to cover your processing costs. The customer pays the fee, and you keep 100% of the sale price. Cash discounting works by offering a lower price to customers who pay with cash, while the "standard" price includes the cost of processing. Both methods are legal in most states, though they have specific signage and disclosure requirements.
These programs are a game-changer for small businesses. Instead of trying to find the lowest possible rate, you are removing the cost from your business entirely. At PayWavez, we specialize in setting up these programs correctly so you stay compliant with card brand rules and state laws. This approach is especially popular in high-traffic areas across the Alabama Gulf Coast, where business owners are tired of seeing their profits eaten away by bank fees.
Avoiding Hidden Fees in Your Merchant Agreement
Even if a company advertises "no monthly fee," you must read the fine print. Some processors hide costs in other places. Look out for PCI non-compliance fees, which can be $20 or more per month if you don't complete a complex questionnaire. Other hidden costs include batch header fees, which are charged every time you close out your terminal for the day, and gateway fees for online transactions. A truly cheap provider will be upfront about every possible charge.
The "Inactivity" Fee Trap
Another common hidden cost is the inactivity fee. Some processors will charge you if you don't process a certain amount of volume within a 90-day period. This defeats the purpose of having a no-monthly-fee account for seasonal businesses. When you sign up, ask specifically if there are any penalties for not using the account. You want a partner that supports your business growth, not one that punishes you for having a slow week.
Equipment Costs: Terminals vs. Mobile Readers
Your choice of hardware also impacts how "cheap" your processing really is. If you only need to take payments occasionally, a mobile card reader that plugs into your phone or connects via Bluetooth is usually the most cost-effective. These readers often cost under $50. However, if you have a physical storefront, a countertop terminal or a full Point of Sale (POS) system might be necessary for efficiency. While these have a higher upfront cost, they offer features like inventory management and employee tracking that can save you time and money elsewhere.
Modern smart terminals are now available that combine the portability of a mobile reader with the power of a full POS. These devices can handle chip cards, contactless payments like Apple Pay, and traditional swipes. Choosing the right equipment ensures you don't overpay for features you don't need while still providing a professional experience for your customers. Remember, the goal is to find the balance between low monthly costs and a system that helps your business run smoothly.
Is a No-Monthly-Fee Account Right for Your Volume?
Finally, you must honestly assess your business volume. A no-monthly-fee account is almost always the right choice for businesses processing under $2,000 a month. Between $2,000 and $5,000, it depends on your average ticket size and the types of cards your customers use. If you find your business is consistently growing, it may eventually be cheaper to pay a $15 monthly fee in exchange for a much lower transaction rate. Regularly reviewing your merchant statements is the only way to ensure you are still on the best plan for your needs.
Don't be afraid to switch providers if your current one is no longer the best fit. The payments industry is highly competitive, and new options for small businesses are appearing every year. By staying informed and looking for transparent, no-monthly-fee options, you can keep your hard-earned money where it belongs: in your business bank account.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.