
Chargeback Management
How to Win a Chargeback Dispute: The Small Business Survival Guide
Dealing with a chargeback dispute shouldn't feel like a losing battle. Here is exactly how to protect your revenue and win when a customer challenges a payment.
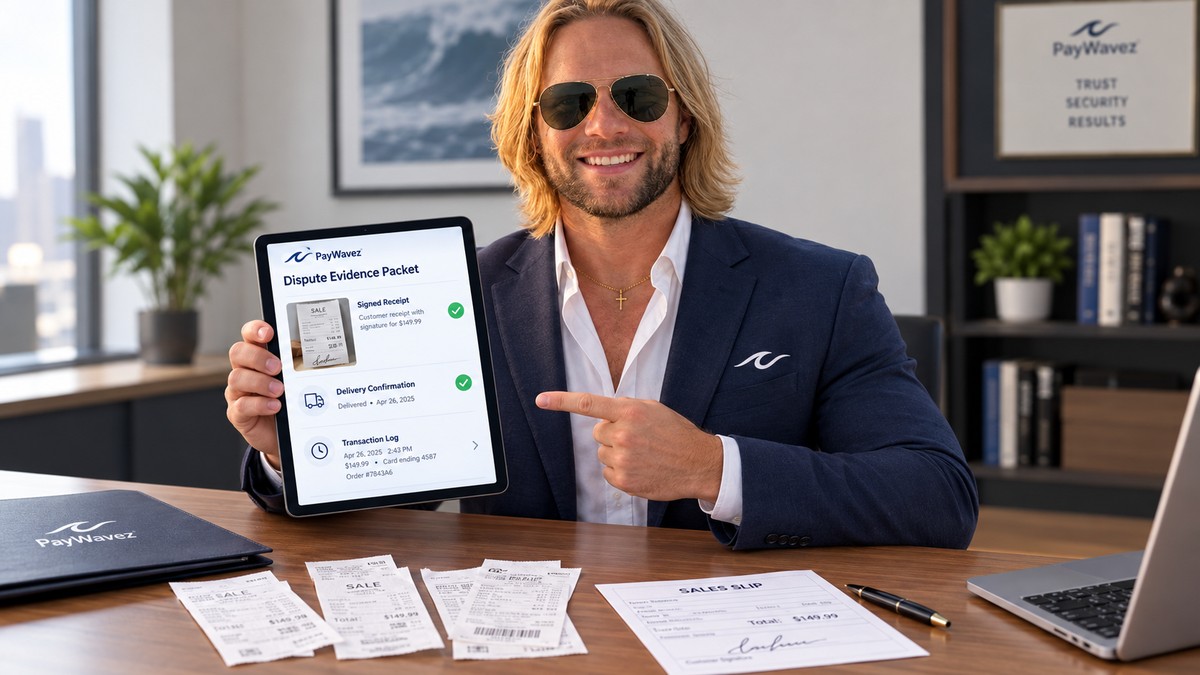
A chargeback dispute is one of the most frustrating parts of running a business that accepts credit cards. One morning you check your merchant account, and instead of a deposit, you see a withdrawal. A customer has told their bank that they don't recognize a charge or that they never received what they paid for. Suddenly, the money is gone from your bank account, and you are hit with a fee that usually ranges from $15 to $50. At PayWavez, we know that for small business owners in places like Alabama payment processing needs to be reliable and transparent, but chargebacks can throw a wrench in even the best cash flow plans.
What Exactly Is a Chargeback?
A chargeback occurs when a cardholder contacts their issuing bank to contest a transaction on their statement. Unlike a refund, which is a voluntary transaction between you and the customer, a chargeback is a forced reversal. The bank takes the money back immediately while they investigate. If you do nothing, you lose the money and the merchandise forever. However, you have the right to fight back. This is known as representment, where you present evidence to prove the transaction was valid.
For many merchants, especially those in tourist-heavy areas like Florida, these issues spike during certain times of the year. For example, business owners using Destin credit card processing often see more disputes during the summer season when travelers might forget a name on a receipt or experience shipping delays for vacation rentals. Understanding the rules of the game is the first step to keeping your revenue safe.
Common Reasons for Cardholder Disputes
Before you can win, you need to know why the customer is complaining. Banks use specific reason codes to categorize every dispute. The most common reasons include "fraudulent transaction," where the customer claims they didn't authorize the purchase, and "service not rendered," where they claim the product never arrived. There is also a growing problem called "friendly fraud." This happens when a customer makes a legitimate purchase but then disputes it because they don't want to pay, they forgot about the purchase, or a family member used the card without asking.
Industry data shows that for every $1 lost to a chargeback, the actual cost to a merchant is roughly $3.75 when you factor in the cost of goods, shipping, processing fees, and the dispute fee itself.
The Step-by-Step Chargeback Dispute Process
When you receive notification of a chargeback dispute, the clock starts ticking. You typically have a very narrow window—often just 14 to 20 days—to respond with your evidence. If you miss this deadline, you lose by default. Here is the standard workflow you can expect:
- Notification: Your merchant processor sends you an alert (via email or your dashboard) that a dispute has been filed.
- Review: You look at the reason code provided by the bank to understand the customer's complaint.
- Evidence Gathering: You collect every piece of data that proves the customer was satisfied or that the transaction followed all security protocols.
- Submission: You send a rebuttal letter and your evidence back to the bank through your processing portal.
- Decision: The bank reviews both sides and makes a final ruling. This can take anywhere from 30 to 90 days.
Using a modern system like the one shown in our live demo can help you track these disputes more effectively, ensuring you never miss a deadline.
Gathering Compelling Evidence
To win, you need facts, not feelings. The bank doesn't care if the customer was rude; they care if you have a signed receipt. If the transaction happened in person, your best evidence is a copy of the receipt showing an EMV chip read. Chip-authenticated transactions are much harder for customers to dispute as "fraud." If you are still swiping magstripe cards, you are likely losing these cases automatically due to the EMV liability shift.
For online or phone orders, you need more digital footprints. This includes the IP address of the person who placed the order, shipping tracking numbers that show "delivered" to the customer's verified address, and any email correspondence where the customer acknowledged the order. If you have a clear refund and cancellation policy, make sure it was visible at the time of purchase. A screenshot of your checkout page showing the "I agree to the terms" checkbox is powerful evidence in a dispute.
A chargeback isn't just a refund; it's a penalty on your business's reputation with the banks. If your ratio gets too high, you risk losing your merchant account entirely.
Writing the Rebuttal Letter
Your rebuttal letter should be professional, concise, and organized. Don't write a five-page essay. Instead, use bullet points. Start by stating the transaction date, the amount, and the authorization code. Then, address the specific reason code. If the customer says they didn't get the item, provide the tracking number and the date of delivery. If they say the item was damaged, show your policy that requires them to return the item for a refund—which they didn't do. Always keep the tone neutral. The bank representative reviewing your case sees hundreds of these a day; make their job easy by highlighting the most important facts first.
The Real Cost of Losing
Losing a dispute is expensive. Beyond the lost sale and the lost item, you are out the original processing fees. Most processors do not refund the interchange fees when a chargeback happens. Furthermore, if your chargeback ratio (the number of disputes vs. your total transactions) goes above 1%, you could be placed in a "monitoring program" by Visa or Mastercard. This leads to even higher fees and could eventually result in your merchant account being terminated. This is why it is almost always worth the effort to fight a dispute if you have the evidence to back it up.
How to Prevent Disputes Before They Happen
Prevention is the best defense. Make sure your "Doing Business As" (DBA) name—the name that appears on the customer's credit card statement—matches what they see on your storefront or website. If a customer buys coffee at "Sunshine Cafe" but the statement says "SC Holdings LLC," they might not recognize it and file a dispute. Also, always use Address Verification Service (AVS) and Card Verification Value (CVV) checks for every transaction. These tools verify that the person using the card actually knows the billing address and has the physical card in hand.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.