
Fee Management
Cash Discount vs. Credit Card Surcharge: Making the Right Choice for Your Bottom Line
Choosing between a cash discount and a credit card surcharge can save your business thousands in fees, but the legal rules and customer reactions are very different.
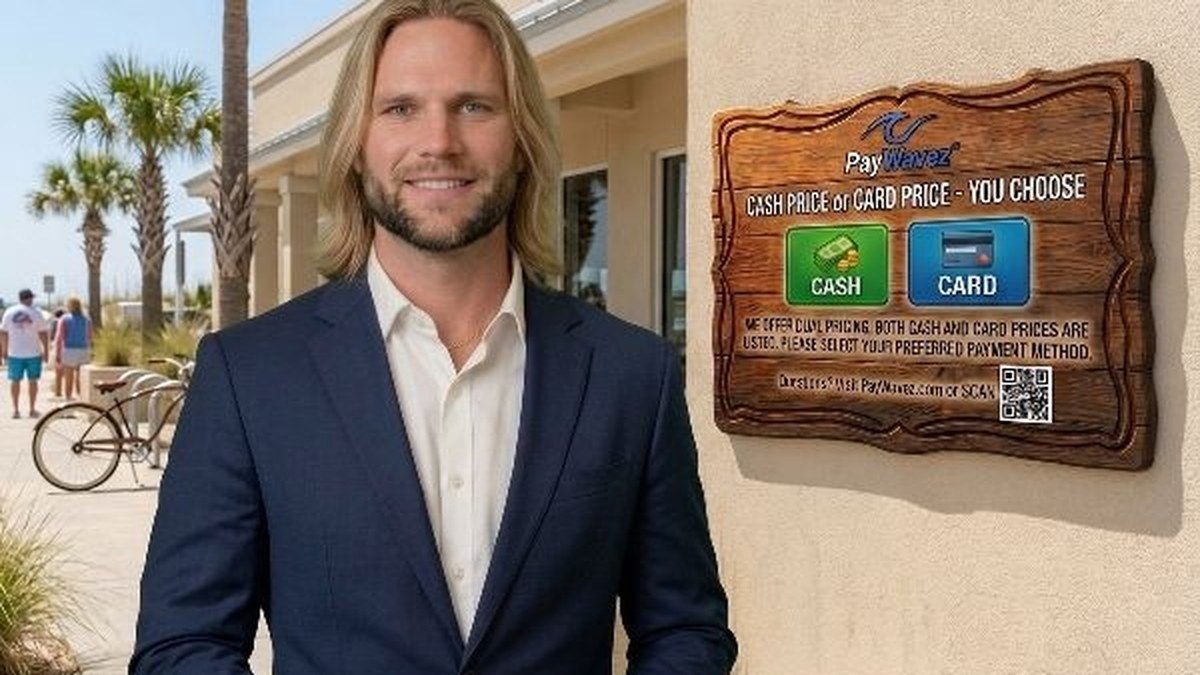
If you are tired of watching a huge chunk of your revenue disappear into credit card processing fees, you have likely looked into pass-through programs. The two most common options are cash discounting and credit card surcharging. While they both aim to protect your margins, they work in very different ways.
At its simplest: a surcharge adds a fee to a credit card transaction at the point of sale. A cash discount offers a lower price to customers who choose to pay with cash or a check. For a deeper dive into the technical mechanics, you can also view our guide on surcharge vs. cash discount programs.
How Credit Card Surcharging Works
Surcharging is the practice of adding a specific percentage (usually between 3% and 4%) to a customer's bill when they pay with a credit card. This fee is meant to cover the cost of the merchant services. However, surcharging comes with strict rules from card brands like Visa and Mastercard:
- Credit Only: You cannot legally surcharge a debit card, even if the customer runs it as "credit."
- Caps: You cannot charge more than your actual cost of processing, and most states cap this at 4%.
- Signage: You must post clear signs at your entrance and the register at least 30 days before you start.
- Registration: You must notify the card brands in writing before implementing a surcharge.
Key Takeaway: Surcharging is highly regulated. If you accidentally surcharge a debit card, you could face heavy fines or lose your merchant account entirely.
How Cash Discounting Works
Cash discounting is often seen as the "safer" alternative. In this model, your displayed prices are your "card prices." If a customer pays with cash, you give them a discount. Because you are offering a reward for cash rather than a penalty for cards, it is legal in all 50 states and does not carry the same "no-debit" restrictions as surcharging.
Many business owners prefer this because it feels more positive to the customer. Instead of seeing a "fee" on their receipt, they see a "discount."
"Surcharging feels like a penalty to the customer, while a cash discount feels like a bonus. In a service-heavy economy, that psychological difference matters."
Comparing the Two: A Decision Table
To help you decide which path to take, consider this breakdown of how these programs impact your daily operations:
| Feature | Credit Card Surcharge | Cash Discount |
|---|---|---|
| Applies to Debit? | No (Illegal) | Yes |
| Legal in all states? | No (Check state laws) | Yes |
| Customer Perception | Negative (Extra fee) | Positive (Savings) |
| Compliance Complexity | High (Card brand rules) | Low (Standard pricing) |
Calculating Your Potential Savings
Before you commit to either program, it helps to know exactly how much money is staying in your pocket. Small businesses often save between $500 and $5,000 per month by moving to a zero-fee model. You can use our Surcharge Savings Calculator to see a side-by-side comparison of your current costs versus a pass-through program.
If you are operating in the Gulf Coast—from our headquarters in Alabama to busy tourist spots like Gulf Shores—managing these fees is essential for surviving the off-season. Tourists are often more forgiving of small fees than locals, so your business location and customer base should play a big role in your choice.
The Verdict
If your business processes a lot of debit cards, a cash discount (or a "Dual Pricing" model) is usually the better choice because it covers all transaction types. If you primarily deal with high-ticket B2B credit card transactions, a surcharge might be simpler to explain. Either way, making the switch can instantly boost your profit margins by 3% or more.
For more details on the legal nuances of these programs, revisit our original breakdown of surcharge vs. cash discount programs or contact us for a free statement review.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.