Merchant Guides
Best Credit Card Processing Services for Business: An Honest 2026 Breakdown
Choosing the right payment partner can save your business thousands of dollars every year. We break down the top providers and show you what to watch out for.
Finding the right credit card processing services for business is one of the most important decisions a new owner can make. In a world where cash is becoming less common, your ability to take plastic and mobile payments safely is the lifeblood of your company. But if you have ever looked at a merchant statement, you know it feels like reading a foreign language. Most providers hide their true costs behind complex jargon and tiered pricing models that make it impossible to know what you are actually paying.
Why You Need Modern Credit Card Processing Services for Business
In 2026, simply "taking cards" isn't enough. Your customers expect to use Apple Pay, Google Pay, and contactless "tap" cards. They want fast transactions and digital receipts. As a business owner, you need more than just a terminal; you need a partner that helps you keep more of your hard-earned money. The market is flooded with options, from massive tech giants to local boutique processors. Choosing the wrong one can lead to locked contracts, expensive equipment leases, and fees that eat up your entire profit margin.
Reliable credit card processing services for business should offer three things: speed, security, and transparency. If your system goes down on a busy Saturday afternoon, you lose money. If your data is breached, you lose your reputation. And if you don't understand your bill, you are likely overpaying. At PayWavez, we believe that payments should be the easiest part of your day, not a source of constant stress.
Key Takeaway: Over 60% of small business owners report that they do not fully understand the fees listed on their monthly merchant statements, leading to billions in unnecessary costs nationwide.
The Truth About Square, Clover, and Toast
When most people start looking for credit card processing, they think of the big names first. Square is famous for its simple flat-rate pricing. It is great for very small startups or hobbyists because there are no monthly fees. However, as you grow, that flat rate (often 2.6% + 10 cents) becomes very expensive compared to other models. Once you are doing more than $5,000 a month, Square's simplicity starts to cost you a lot of money.
Clover offers beautiful hardware and a massive app market. It is a powerful system, but it is often sold through big banks. This means you might end up with a long-term contract and a high monthly bill for software you don't even use. Toast is the king of the restaurant world, but they are known for "locking in" merchants and making it very difficult to switch if you are unhappy with their rising rates. Each of these has its place, but they aren't always the best fit for a merchant who wants a personal relationship and low, transparent costs.
How to Spot Hidden Fees on Your Statement
If you want to know if you are being overcharged, you have to look past the "teaser rate." Many providers will promise a rate of 1.5%, but that only applies to a small number of cards. Most of the cards your customers use—like rewards cards, business cards, and international cards—will be "downgraded" to a much higher rate. This is called tiered pricing, and it is a major red flag.
- PCI Compliance Fees: Some companies charge $20 or $30 a month just to "check" that you are secure. This should be a simple annual process, not a monthly cash grab.
- Statement Fees: You shouldn't have to pay $15 a month just to receive a bill.
- Batch Header Fees: A small fee charged every time you close out your terminal for the day. It seems small, but it adds up over 30 days.
- Annual Fees: Many legacy processors charge a "membership" fee once a year for no clear reason.
"A merchant account shouldn't be a black box. If your processor can't explain every single line item on your statement in plain English, it is time to find a new partner."
The Power of Dual Pricing and Surcharging
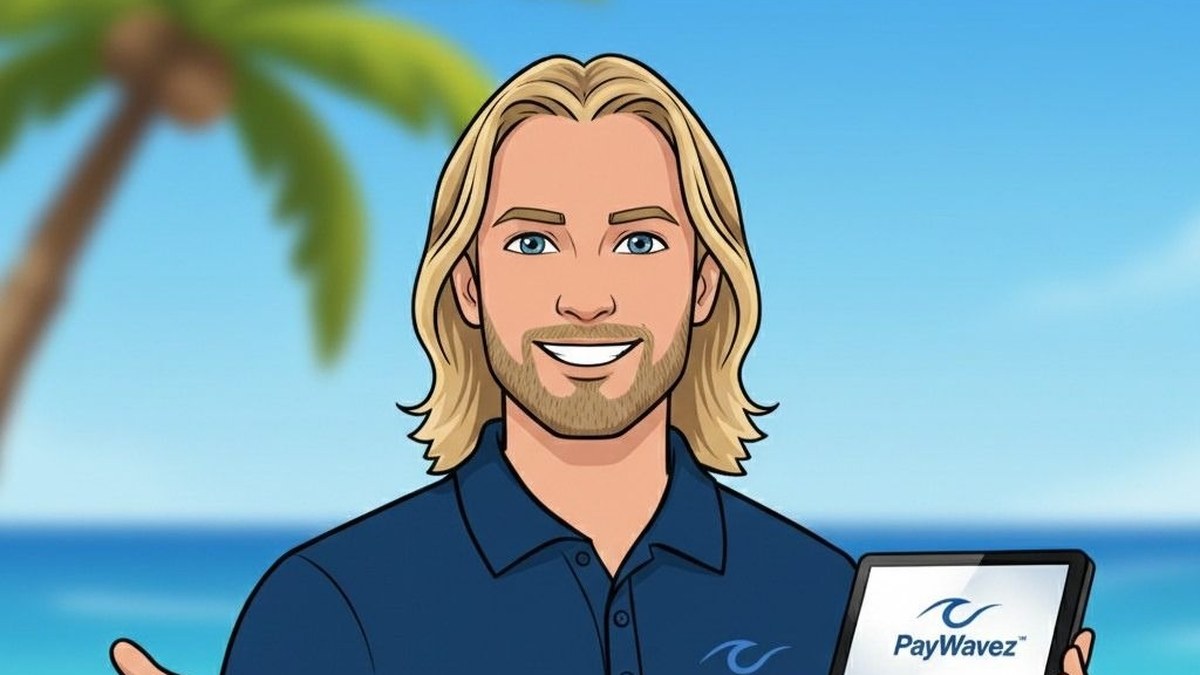
One of the biggest shifts in credit card processing services for business is the move toward dual pricing. This is a strategy that allows businesses to offer a cash price and a card price. When a customer pays with a card, a small service fee is added to cover the cost of the processing. This allows the merchant to keep 100% of the sale price. For a business doing $50,000 a month in sales, this can save nearly $20,000 a year in fees.
PayWavez specializes in setting up these programs legally and transparently. We provide the signage and the programmed terminals so that the process is seamless for your customers. Most customers today understand that processing costs money, and they are happy to support a local business by paying a small fee or choosing to pay with cash to get the discount. You can see how this looks in action by checking out our live demo.
Choosing the Right Hardware for Your Shop
Your hardware is the physical touchpoint between you and your customer. You want something that looks professional and works every time. We offer everything from mobile readers for contractors to full-scale point-of-sale systems for retail stores. If you are a mobile business, you need a long-lasting battery and a strong cellular connection. If you have a brick-and-mortar shop, you might want a customer-facing screen that allows for easy tipping and signature capture.
We often recommend "smart" terminals like the Dejavoo or PAX lines. These devices are much more powerful than the old "grey boxes" of the 90s. They connect to Wi-Fi, have touchscreens, and can even track your inventory. Best of all, they are often much more affordable than the proprietary hardware sold by companies like Clover or Toast.
How to Switch Without Losing Sales
Many business owners stay with a bad processor because they are afraid of the "downtime" during a switch. They worry that they won't be able to take cards for a day or two. With a professional setup, there is zero downtime. We ship you the pre-programmed equipment, you plug it in, and you run a test transaction. Once you know it works, you simply stop using the old machine. It is that simple.
We also help you navigate the cancellation process with your old provider. Some of them make it intentionally difficult to leave, but we know the tricks they use. We can review your current contract to see if there are liquidation fees or notice periods you need to be aware of. Our goal is to make the transition as smooth as possible so you can start saving money on day one.
Why Local Support Matters for Gulf Coast Merchants
When you use a massive national processor, you are just a number in a database. If your terminal breaks, you call a 1-800 number and wait on hold for an hour. For businesses on the Gulf Coast, having a local partner makes a huge difference. We understand the seasonal nature of tourism and the specific needs of businesses in our area. Whether you need Pensacola credit card processing or help anywhere else along the coast, we are just a phone call away.
Our Alabama payment processing hub serves merchants from Mobile to the beach, providing on-site support that the big tech companies can't match. We live where you live, and we want to see our local economy thrive by helping small businesses keep more of their revenue.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.