
E-commerce Payments
Finding the Best Credit Card Merchant for Online Store Success
Choosing the right payment partner is the most important step for any e-commerce business. This guide breaks down how to find the best rates and features for your online shop.
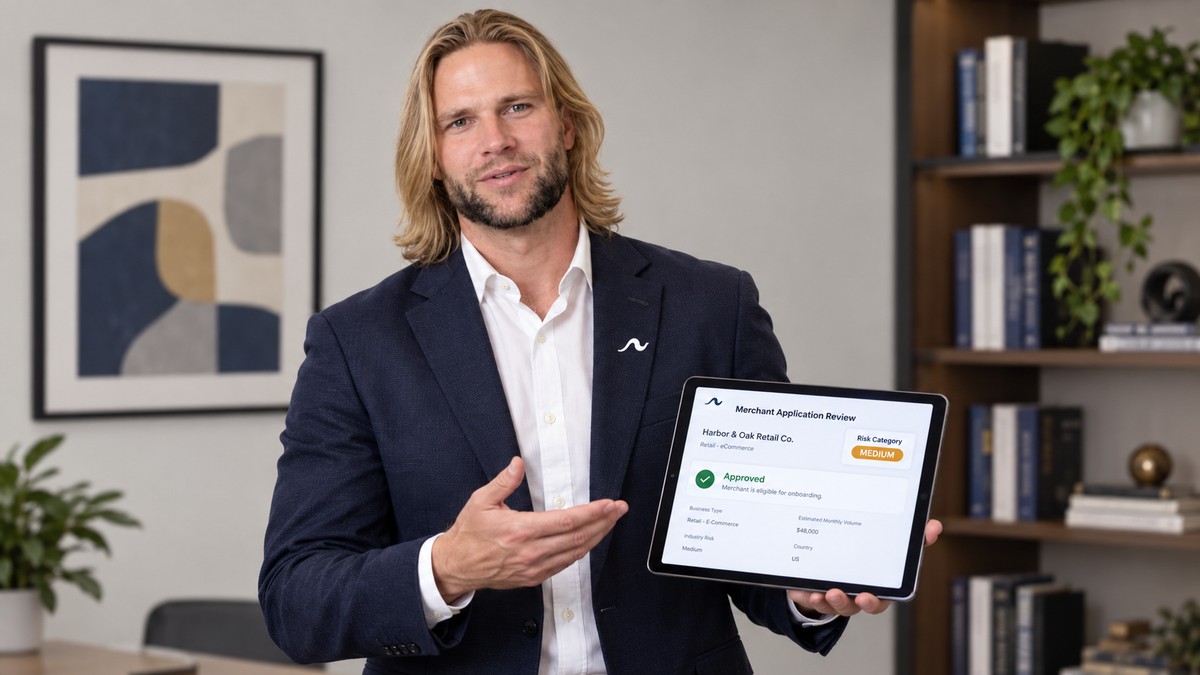
The best credit card merchant for online store owners is one that balances low transaction fees with high-level security and reliable customer support. When you start selling products on the internet, you quickly realize that not all payment processors are created equal. Some may look cheap at first but hide fees in the fine print. Others might offer great software but freeze your funds the moment you have a busy sales weekend. For a small business owner, these disruptions can be devastating. You need a partner that understands the specific challenges of digital commerce, from handling card-not-present transactions to fighting off fraudulent chargebacks.
Aggregators vs. Dedicated Merchant Accounts
Most new online sellers start with a payment aggregator. These are companies like Square, Stripe, or PayPal. They are popular because you can sign up in minutes and start taking payments immediately. However, an aggregator lumps your business into one giant merchant account with thousands of other businesses. This sounds convenient, but it comes with risks. If another business in that giant pool does something suspicious, the aggregator might freeze everyone’s funds or suddenly close accounts without warning. This is a common nightmare for small business owners who rely on steady cash flow.
A dedicated merchant account is different. With this setup, you have your own unique account with a processing bank. The underwriting happens before you start processing, which means your account is much more stable. While it takes a little longer to set up, it offers lower rates as you grow and much better security for your money. For any business planning to stay in operation for more than a few months, a dedicated account is almost always the superior choice.
Understanding E-commerce Processing Fees
Online sales are classified as "card-not-present" (CNP) transactions. Because the physical card isn't being swiped or dipped into a terminal, banks consider these transactions to be higher risk. To cover this risk, processing fees for online stores are usually higher than those for a brick-and-mortar shop. These fees are generally made up of three parts: interchange fees (paid to the bank that issued the card), assessment fees (paid to the card brand like Visa or Mastercard), and the processor's markup.
According to industry data, the average cost of a card-not-present transaction ranges from 2.3% to 3.5%, depending on the card type and the merchant's industry risk level.
When searching for the best credit card merchant for online store use, you should look for "interchange-plus" pricing. This is the most transparent way to pay. It means the processor charges you the exact cost of the interchange fee and then adds a small, fixed markup. This is much better than "tiered pricing," where the processor groups transactions into categories like "qualified" and "non-qualified," often hiding the true cost of the transaction from the merchant.
Features of the Best Credit Card Merchant for Online Store Growth
To truly support your growth, a merchant service provider must offer more than just a way to swipe a card. They need to provide a robust payment gateway. The gateway is the software that sits between your website and the processing network. It encrypts the customer's data and ensures the money moves safely from their bank to yours. A high-quality gateway will include features like a virtual terminal, which allows you to take orders over the phone and enter them manually into a secure web browser.
Another key feature is recurring billing. if you sell subscriptions or have repeat customers, you want a system that can store card data securely (tokenization) and charge it on a schedule. This reduces the friction for your customers and ensures you get paid on time every month. Additionally, look for a provider that offers detailed reporting. You should be able to see exactly which transactions were processed, what the fees were for each, and when the money will hit your bank account. Transparency in reporting is a hallmark of a trustworthy processing partner.
"A merchant account isn't just a utility; it's the engine of your digital storefront. If the engine stalls, your entire business stops moving."
Preventing Fraud and Managing Chargebacks
Fraud is a major concern for online sellers. Since you never see the customer or the card, it is easier for criminals to use stolen data. The best credit card merchant for online store operations will provide built-in fraud tools. These tools check things like the Address Verification Service (AVS) and the CVV code on the back of the card. Some advanced systems even use machine learning to flag suspicious patterns, such as a customer placing ten orders in five minutes from three different countries.
Chargebacks occur when a customer disputes a charge with their bank. In the online world, this happens often. Sometimes it is legitimate, like a package that never arrived. Other times, it is "friendly fraud," where a customer tries to get a refund while keeping the product. Your processor should help you fight these. They should provide a clear portal where you can upload evidence, such as shipping receipts and delivery confirmations, to prove the transaction was valid. Managing chargebacks effectively can save your business thousands of dollars a year.
Surcharging and Dual Pricing for Online Sales
One of the biggest expenses for an online store is the processing fee itself. Many merchants are now turning to surcharging or dual pricing programs to offset these costs. Surcharging is when you add a small fee (usually around 3% to 4%) to the total if the customer chooses to pay with a credit card. This passes the cost of the processing directly to the consumer. While this was once restricted to physical stores, many modern gateways now allow for online surcharging.
Dual pricing is a similar concept where you show two prices: a "cash" price (or ACH/debit price) and a "card" price. This is often better received by customers because it feels like a discount for using a cheaper payment method rather than a penalty for using a credit card. Before implementing these, you must ensure your processor follows all state and card brand rules. For example, you cannot surcharge on debit cards, even if they are processed online. Having a partner who understands these legal nuances is vital to avoiding heavy fines.
Local Support for Gulf Coast Merchants
While e-commerce is global, having local support can make a huge difference when things go wrong. If you are a business owner in the Southeast, you might prefer working with a company that understands the local economy. For example, many businesses in Pensacola or along the Alabama coast deal with seasonal swings in sales. A local provider can help you adjust your account settings or hardware needs based on these cycles.
Whether you are looking for Alabama payment processing or support in a neighboring state, having a dedicated representative you can call—rather than a generic call center—is a massive advantage. When your website's checkout stops working at 8:00 PM on a Friday, you don't want to be on hold for two hours. You want a partner who knows your name and your business and can get you back up and running quickly.
How to Switch Processors Without Downtime
Many business owners stay with a bad processor because they are afraid that switching will break their website. However, switching can be seamless if done correctly. The first step is to get a statement review to see exactly how much you can save. Once you choose a new provider, you set up the new gateway in the background. You can even run test transactions to ensure everything is communicating correctly with your website's shopping cart.
Once the new system is verified, you simply swap the API keys in your website settings. This transition takes only a few seconds. You should keep your old account open for at least 30 days to handle any returns or chargebacks from old transactions. After that, you can close the old account and enjoy the lower rates and better service of your new partner. Don't let the fear of a small technical task keep you trapped in a high-fee contract.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.