
Fees & Rates
Payment Processing Fees: The Complete Guide for Small Business Owners
Understanding every line item on your merchant statement is the first step toward keeping more of your hard-earned revenue.
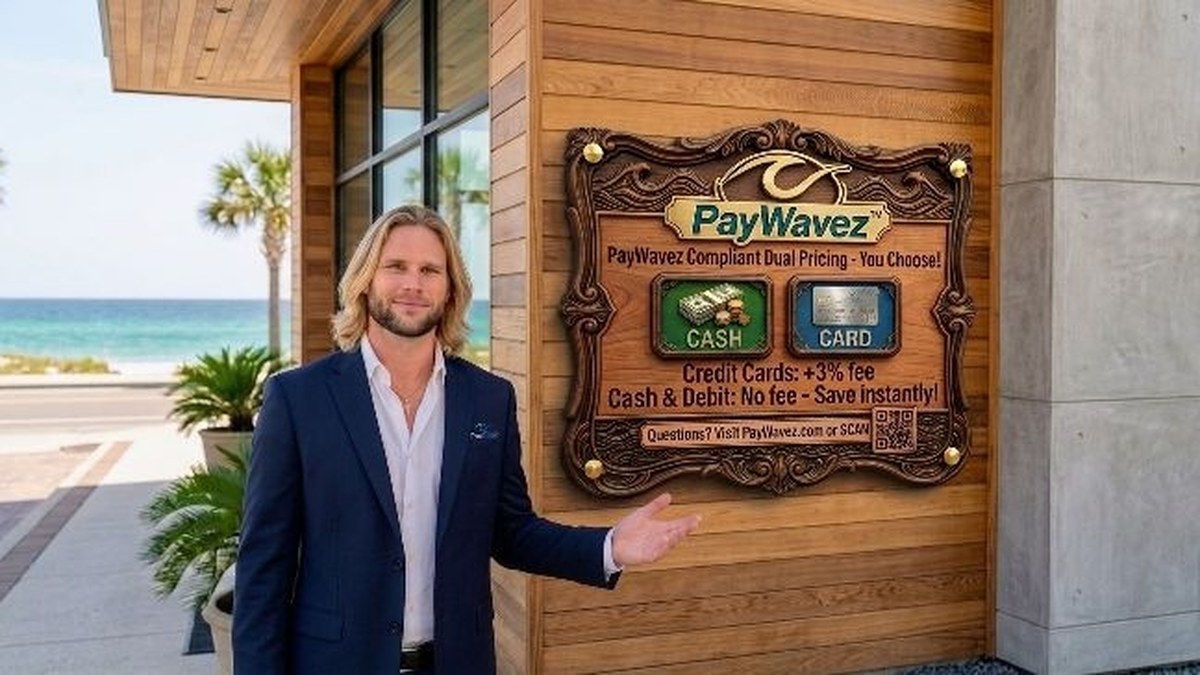
Payment processing fees are often the single largest expense for a small business after payroll and rent. When you swipe a customer's card, a small percentage of that sale disappears before it ever reaches your bank account. If you want to understand the foundations of these costs, we recommend reading our post on merchant services fees explained to get a head start. In this guide, we will go much deeper into how these fees are built, how to spot the ones you shouldn't be paying, and how to use modern programs like dual pricing to eliminate them entirely.
The Three Layers of Every Transaction
Every time a credit card is processed, the total fee is actually made up of three different parts. These parts are collected by different companies involved in the transaction. First is the interchange fee. This is the largest part and goes directly to the bank that issued the customer's card (like Chase or Wells Fargo). Second are the assessment fees. These are small, non-negotiable amounts paid directly to the card brands like Visa, Mastercard, and Discover. Finally, there is the processor markup. This is the amount your merchant services provider charges for their service. This is the only part of the fee that is truly negotiable.
Understanding this breakdown is vital because many processors will hide their markup inside a high flat rate. If you are paying a flat 2.9% for every transaction, you might be overpaying on debit cards, which have much lower interchange rates than premium rewards credit cards. Knowing where the money goes allows you to see if your provider is being fair or if they are padding their profits at your expense.
Industry data shows that the average merchant pays between 1.5% and 3.5% in total fees, but businesses using legacy flat-rate models often pay 20% more than those on interchange-plus pricing.
How to Spot Hidden Payment Processing Fees on Your Statement
Many business owners stop looking at their merchant statement once they see the total amount deducted. However, the devil is in the details. Some of the most common hidden costs include PCI non-compliance fees. These are monthly charges (often $20 to $100) billed to you simply because you haven't filled out a yearly security questionnaire. Other common additions include "statement fees," "batch header fees," and "regulatory product fees." While a few dollars here and there might not seem like much, they add up to hundreds of dollars a year that provide zero value to your business.
You should also look for "tiered pricing" traps. In this model, transactions are labeled as qualified, mid-qualified, or non-qualified. The processor advertises a very low rate for "qualified" transactions, but almost no modern cards actually qualify for that rate. Most cards, like business cards or travel rewards cards, get pushed into the higher tiers, resulting in much higher costs than you originally signed up for. Transparency is key to a healthy merchant relationship.
The most expensive fee is the one you do not know you are paying; transparency in your merchant statement is the only way to protect your profit margins.
Interchange-Plus vs. Flat-Rate Pricing
Choosing the right pricing model is one of the most important decisions you will make. Flat-rate pricing, popularized by companies like Square, is simple to understand. You pay one percentage regardless of the card type. While this is easy for bookkeeping, it is usually the most expensive option for established businesses. You are essentially paying a premium for that simplicity.
Interchange-plus pricing is the gold standard for transparency. Your processor passes through the exact cost of the interchange and assessments, then adds a small, fixed markup on top. This ensures that when a customer uses a low-cost debit card, you actually see the savings instead of the processor pocketing the difference. For businesses in high-volume areas like our Pensacola credit card processing clients, switching to interchange-plus can save thousands of dollars annually.
The Power of Dual Pricing and Surcharging
What if you could eliminate your costs almost entirely? This is where surcharging and dual pricing programs come in. These programs allow you to pass the cost of the credit card transaction directly to the customer who chooses to use a card. In a dual pricing setup, you display a cash price and a card price for every item. If a customer pays with cash, they get the lower price. If they use a card, the processing fee is built into the card price.
This is legally different from a simple surcharge, and it is becoming the preferred method for small businesses across the country. It allows you to maintain your profit margins without having to raise prices for everyone. We help businesses from our Alabama payment processing hub implement these programs legally and with the correct signage to ensure a smooth customer experience. You can see how this looks for a business by checking out our live demo.
Equipment and POS System Costs
Beyond the percentage fees, you must consider the hardware. Some processors will offer "free" terminals, but these often come with long-term contracts or higher monthly rates that cost more in the long run. Buying your equipment outright or using a modern smart terminal like Clover can often be more cost-effective. A good POS system should do more than just take payments; it should help you track inventory, manage employees, and run reports that help you grow.
Ensure your terminal is PCI compliant and supports EMV chip cards and contactless payments like Apple Pay. Using outdated equipment can lead to higher fees and increased liability for fraud. If you are still swiping cards instead of dipping the chip, you are likely paying "non-qualified" rates because the transaction is considered higher risk. Upgrading your hardware is often the fastest way to lower your per-transaction costs.
Chargebacks and Operational Fees
A chargeback occurs when a customer disputes a charge with their bank. Not only do you lose the sale amount, but the processor also charges you a chargeback fee, usually between $15 and $50. If your business has too many chargebacks, your processor may even shut down your account or place you in a "high-risk" category with even higher payment processing fees.
To prevent this, always use clear descriptors on your bank statements so customers recognize the charge. Provide receipts for every transaction and have a clear refund policy. If you run a service business, getting a signature on a work order or contract can help you win disputes if they arise. Managing your operations well is just as important as negotiating your rates when it comes to the bottom line.
Conclusion: Taking Control of Your Rates
Navigating the world of merchant services doesn't have to be a headache. By understanding the different layers of costs and knowing how to spot hidden markups, you can ensure your business isn't being taken advantage of. Remember to review your statements monthly and look for any new fees that might have appeared without notice. If you ever feel lost, reviewing our guide on merchant services fees explained is a great way to refresh your knowledge. At PayWavez, we believe in total transparency and helping small business owners keep the money they earn. Whether you are looking for a new POS system or want to explore a zero-fee processing model, we are here to help you find the right fit.
Ready to see your own numbers?
Run your real card volume through the calculator or apply in about two minutes.